Speak with a licensed insurance agent

1-888-891-0229

Manhattan Life Cancer Insurance: Plans, Benefits and Ratings

Updated October 2026

Key Takeaway

Manhattan Life cancer insurance is supplemental, limited-benefit coverage that pays cash to you after a covered cancer diagnosis or treatment. Its current lineup centers on Cancer Care Plus, a benefit-schedule plan, and a lump sum Cancer and/or Heart Attack and Stroke policy.

ManhattanLife is a Houston-based insurance group that sells life insurance, annuities and supplemental health coverage, including several cancer plans. Its cancer policies are sold through licensed agents, and benefits are paid to you rather than to your doctor or hospital.

This guide covers what each Manhattan Life cancer policy is built to do, how the benefits pay, what changed in 2026, and how the company compares with other cancer insurance providers. One point applies to every plan on our cancer insurance site: this coverage adds cash on top of your health plan. It does not replace health insurance.

Compare Cancer Insurance Plans

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

Who Is ManhattanLife?

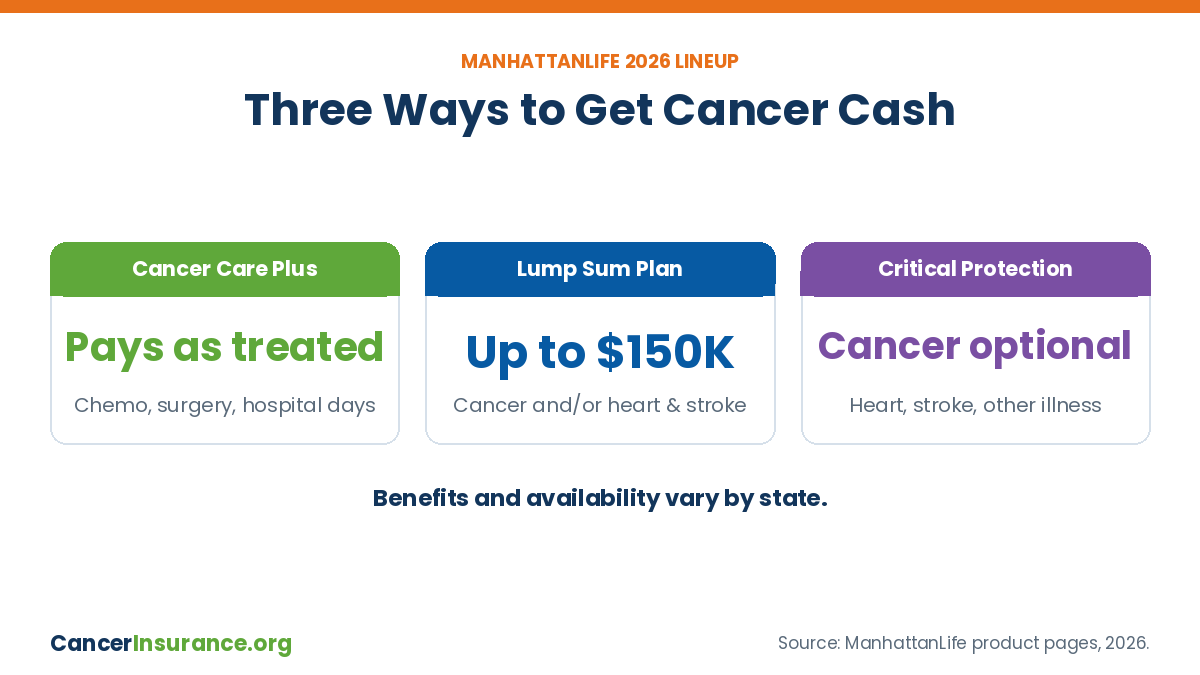
Manhattan Life cancer insurance plan lineup for 2026 with Cancer Care Plus, lump sum and critical illness options

ManhattanLife is a brand name used by several affiliated insurance companies with offices at 10777 Northwest Freeway in Houston, Texas. Depending on the plan and your state, your policy may be issued by The Manhattan Life Insurance Company, ManhattanLife Insurance and Annuity Company, ManhattanLife Assurance Company of America, Family Life Insurance Company or Standard Life and Casualty Insurance Company. The company that stands behind your coverage is named on your contract.

Supplemental health focus. Besides cancer plans, ManhattanLife sells life insurance, annuities and other supplemental health plans, including critical illness coverage.

Sold through agents. Policies are sold by licensed agents and brokers, so you can compare ManhattanLife next to other companies in one sitting.

Plans for many ages. Its cancer brochures show plans for working-age adults as well as people old enough for Medicare. Issue ages differ by plan.

State rules apply. ManhattanLife states that not all plans, products and riders are available in every state.

Cancer Insurance Quotes

Call a Licensed Agent Now

Compare cancer insurance plans and cash benefits from several insurance companies in one call.

☎ 1-888-891-0229

No obligation to buy

Manhattan Life Cancer Insurance Plans in 2026

In January 2026, ManhattanLife announced that its stand-alone Cancer First Occurrence Benefit product would stop being sold on February 1, 2026. People who already own it keep their coverage as long as they pay premiums. New buyers are pointed to three other plans.

PlanWhat it coversHow it pays
Cancer Care PlusCancer plus specified diseases such as multiple sclerosis, muscular dystrophy, epilepsy and meningitisSet amounts for listed treatments, hospital days, surgery and travel
Cancer and/or Heart Attack & StrokeCancer only, heart attack and stroke only, or bothLump sum, up to $150,000 when both parts are combined
Critical Protection and RecoveryHeart attack, stroke and other critical illnesses, with cancer as an optionFirst occurrence, hospital and monthly income benefits

Based on ManhattanLife product pages and its January 2026 announcement. Benefits, riders and availability vary by state.

If you want to line up these plans side by side, see our full guide to compare Manhattan Life cancer insurance plans.

How Manhattan Life Cancer Insurance Pays Benefits

The two main Manhattan Life cancer policies pay in very different ways. Knowing the difference helps you pick the right one.

1

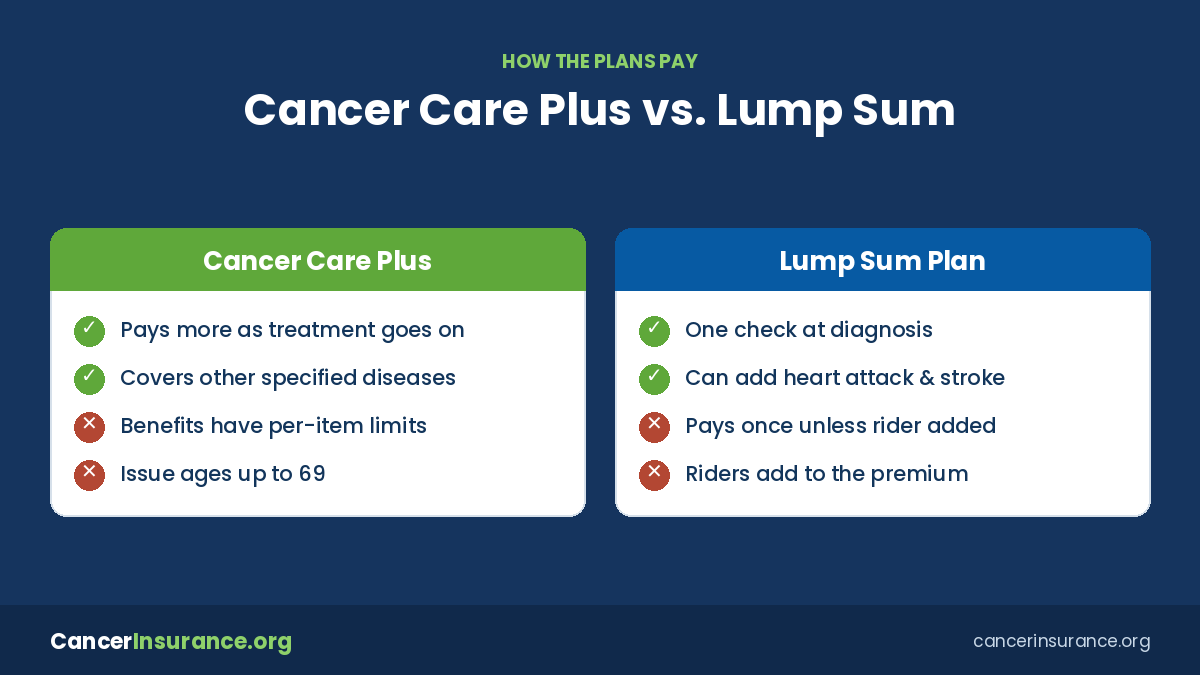
Cancer Care Plus pays as treatment happens. It pays scheduled amounts for things like radiation and chemotherapy, surgery, hospital days, prescribed drugs, hospice and travel to treatment. A brochure we reviewed shows chemotherapy and radiation paying actual charges up to a monthly limit, and hospital stays paying a set daily amount for the first 70 days of each stay.

2

The lump sum plan pays once at diagnosis. The Cancer and/or Heart Attack and Stroke policy pays one cash amount when a covered diagnosis is confirmed. ManhattanLife says you choose how to use the money.

3

Riders can add more. Cancer Care Plus offers an Intensive Care Unit rider and a Critical Care rider. The lump sum plan offers a Cancer Recurrence rider and a Heart and Stroke Restoration rider.

4

Payments go to you. Benefits are paid on top of what your health plan or Medicare pays, so you can use them for deductibles, rent, gas or lost income.

Good to know: Both policies exclude cancer diagnosed before the policy starts and cancer diagnosed during the waiting period. Diagnoses made outside the United States and its territories are also excluded. Ask the agent for the exact waiting period in your state.

Manhattan Life Benefit Amounts and Eligibility

Manhattan Life cancer insurance Cancer Care Plus compared with the lump sum cancer plan

ManhattanLife does not list prices on its website, and amounts depend on the plan, your age and your state. Here is what its brochures show.

Cancer Care Plus ages. A Cancer Care Plus brochure lists issue ages 18 to 69. Its First Occurrence rider pays $1,000 to $10,000 once and is not available at age 65 or older.

Lump sum amounts. A lump sum brochure shows cancer and heart and stroke benefits from $5,000 to $75,000 each, with rates shown for ages 20 to 84.

Recurrence rider. If cancer returns, the rider pays a share of the original amount based on how long you went without treatment, from 25% after two years up to 100% after ten.

Renewal. The Cancer Care Plus brochure states its plans are guaranteed renewable, so they can’t be cancelled because your health changes while you pay premiums. Rates can still change for a whole class of policyholders.

For premium ranges and what drives them, see our page on Manhattan Life cancer insurance cost. Your actual price depends on your age, the benefit level you pick and any riders you add.

Compare Cancer Insurance Plans

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

ManhattanLife AM Best Rating, Pros and Cons

In January 2022, AM Best upgraded the financial strength rating of the Manhattan Insurance Group companies to B++ (Good) from B+ (Good), with a stable outlook. That is a solid rating, but it sits below the A-range ratings held by some larger cancer insurance companies. Ask your agent for the current rating of the company named on your policy.

ProsCons
Choice between a benefit-schedule plan and a lump sum planStand-alone Cancer First Occurrence plan is no longer sold
Lump sum can reach $150,000 when cancer and heart are combinedB++ (Good) rating is below some competitors
Cancer Care Plus also covers several other specified diseasesBenefit amounts and riders vary by state
Cash is paid directly to youRecurrence and restoration riders cost extra

Broker tip: If your main fear is the cost of a long treatment, Cancer Care Plus pays more as treatment goes on. If you want one fast check to cover income loss and deductibles, the lump sum plan is the simpler choice.

Is Manhattan Life Cancer Insurance Right for You?

ManhattanLife fits people who want flexible plan designs and are comfortable with a B++ rated company. Employer, ACA and Medicare readers all use these plans the same way: as extra cash that sits beside major medical coverage.

1

Check your out-of-pocket maximum. Your health plan’s deductible and out-of-pocket limit show how big a gap you may face.

2

Pick a payment style. Choose between ongoing treatment benefits and a single lump sum.

3

Decide on heart coverage. Adding heart attack and stroke to the lump sum plan widens protection but raises the premium.

4

Compare other companies. Look at ManhattanLife next to the plans in our 5 best cancer insurance policies list before you apply.

A licensed agent who works with several companies can show ManhattanLife quotes beside other cancer insurance plans so you can see which pays more for your budget.

Bottom Line

Manhattan Life cancer insurance gives you two main ways to get cash after a cancer diagnosis: Cancer Care Plus, which pays as treatment happens, and a lump sum plan that can also cover heart attack and stroke. It is supplemental coverage from a B++ (Good) rated group, so compare it with other companies before you decide.

Get Free Cancer Insurance Quotes

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

Manhattan Life Cancer Insurance — Frequently Asked Questions

➤ What cancer plans does ManhattanLife sell?

Its current cancer lineup includes Cancer Care Plus, a lump sum Cancer and/or Heart Attack and Stroke policy, and Critical Protection and Recovery with an optional cancer benefit. Availability varies by state.

➤ Did ManhattanLife discontinue a cancer plan?

Yes. ManhattanLife announced that its Cancer First Occurrence Benefit product would no longer be sold after February 1, 2026. Existing policies stay in force as long as premiums are paid.

➤ Does Manhattan Life cancer insurance pay a lump sum?

The Cancer and/or Heart Attack and Stroke policy pays a lump sum after a covered diagnosis, up to $150,000 when cancer and heart coverage are combined. Cancer Care Plus mainly pays set amounts for treatments, with an optional one-time first occurrence benefit.

➤ What is ManhattanLife’s AM Best rating?

In January 2022, AM Best upgraded the Manhattan Insurance Group companies to a financial strength rating of B++ (Good) with a stable outlook. Check the current rating for the company named on your policy.

➤ Who can buy Manhattan Life cancer insurance?

Issue ages depend on the plan. A Cancer Care Plus brochure lists ages 18 to 69, and a lump sum brochure shows rates for ages 20 to 84. Health questions and state rules also apply.

➤ Does Manhattan Life cancer insurance replace health insurance?

No. It is a supplemental, limited-benefit policy that pays set cash amounts. You still need health insurance, Medicare or another major medical plan to pay your treatment bills.

➤ Is there a waiting period?

Yes. Cancer diagnosed during the waiting period is not covered, and the heart attack and stroke part of the lump sum plan has a 30-day waiting period. Ask your agent for the cancer waiting period in your state.

➤ Who pays the benefit, me or the hospital?

Benefits are paid to you. You can use the money for medical bills, travel to treatment, household bills or lost income.
Cancer Insurance Quotes

Call a Licensed Agent Now

Compare cancer insurance plans and cash benefits from several insurance companies in one call.

☎ 1-888-891-0229

No obligation to buy

Ready to Compare? Get Free Cancer Insurance Quotes

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

ZRN Health & Financial Services, LLC, a Texas limited liability company