Speak with a licensed insurance agent

1-888-891-0229

Is Mutual of Omaha Cancer Policy Worth It? Value, Limits and Who It Fits

Updated October 2026

Key Takeaway

A Mutual of Omaha cancer policy is worth it for many adults who want one large, flexible cash payment if cancer is diagnosed, especially those over 55 who want lifetime coverage with no benefit cut at older ages. It is less of a fit if you want ongoing payments through long treatment.

Mutual of Omaha is a household name, and its cancer coverage is easy to understand: pick a benefit amount, and if you are diagnosed with a covered cancer, you get a check for that amount. Simple is good, but simple is not automatically worth the premium. The answer depends on how you would use the money and what else you already have.

Below we weigh what the policy pays against its limits, run through who tends to get the most value, and compare it with other designs. For the full feature list, see our Mutual of Omaha cancer insurance overview. Like all cancer coverage, this is a supplemental, limited-benefit policy and does not replace health insurance.
Compare Cancer Insurance Plans

Speak with a licensed insurance agent

1-888-891-0229

What You Get for Your Premium

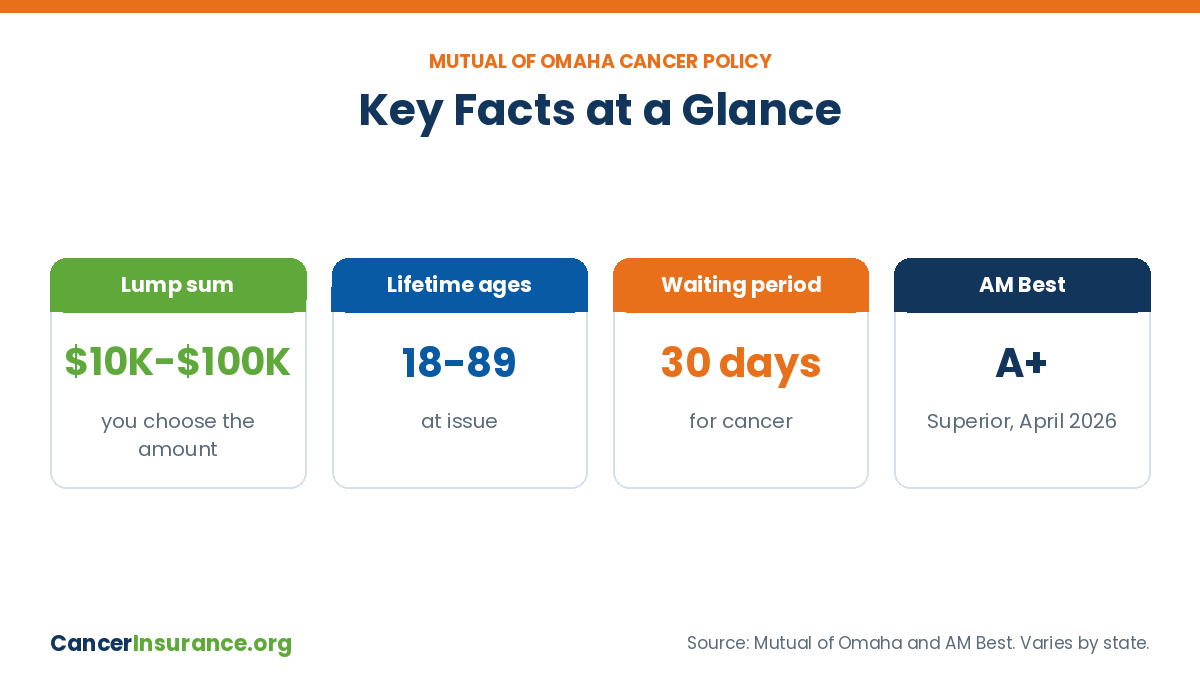
Is Mutual of Omaha cancer policy worth it at a glance with benefit range, ages, waiting period and rating

Mutual of Omaha’s main cancer product is a lump-sum policy underwritten by Mutual of Omaha Insurance Company. You choose a benefit between $10,000 and $100,000. If you are diagnosed with a covered internal cancer or malignant melanoma, the policy pays 100% of that amount to you in one payment, not to your doctors.

You can buy it as lifetime coverage or as a term policy of 10, 15, 20 or 30 years, and you can cover just yourself or add children or a spouse. Mutual of Omaha also offers a heart attack and stroke policy and a broader critical illness policy for people who want more than cancer covered.

One clear payout. The full benefit you picked is paid once for a covered diagnosis. No bills to submit for each treatment.

Spend it any way. Use the money for deductibles, travel, rent, child care or lost pay.

No age cut. Mutual of Omaha’s materials say the benefit is not reduced as you get older.

Cancer Insurance Quotes

Call a Licensed Agent Now

Compare cancer insurance plans and cash benefits from several insurance companies in one call.

☎ 1-888-891-0229

No obligation to buy

The Numbers That Decide Value

These are the key terms from Mutual of Omaha’s product materials. Your state can change some of them, so ask for the outline of coverage where you live.

FeatureMutual of Omaha cancer policy
Benefit amount$10,000 to $100,000, your choice
Issue ages18 to 89 for lifetime coverage; 18 to 54 for term
Term optionsLifetime, or 10, 15, 20 or 30 years
Who can be coveredIndividual, individual plus children, or family
Waiting periodCancer first diagnosed in the first 30 days is not covered
Health questionsShorter express process up to $50,000; simplified process from $51,000 to $100,000
RenewabilityGuaranteed renewable as long as premiums are paid

Source: Mutual of Omaha product pages and brochure. Features and availability vary by state.

The age range is a standout. Many cancer policies stop selling to people in their 70s or early 80s, while Mutual of Omaha’s lifetime version can be bought up to 89. Prices depend on your age, benefit amount, coverage type and state. See Mutual of Omaha cancer insurance cost for how premiums are set.

Limits That Can Lower the Value

A policy is only worth it if it pays when you need it. These rules are where claims most often fall short.

30-day wait. Cancer first diagnosed within 30 days of the effective date is not covered. In Pennsylvania, a cancer found in that window can be covered after two years.

Narrow definition. The policy covers internal cancer and malignant melanoma. Precancerous conditions such as benign moles, leukoplakia and hyperplasia do not count.

Built for a first diagnosis. It pays one lump sum for the covered diagnosis. It is not designed to keep paying for each round of treatment.

Health history matters. A prior cancer, or a cancer diagnosed before the policy starts, can mean a decline or no benefit.

Broker tip: Do not drop an existing cancer policy until a new one is approved and past its 30-day wait. Our guide to cancer insurance waiting periods explains why.

Who Gets the Most From Mutual of Omaha

Is Mutual of Omaha cancer policy worth it showing who it fits and who may want another plan

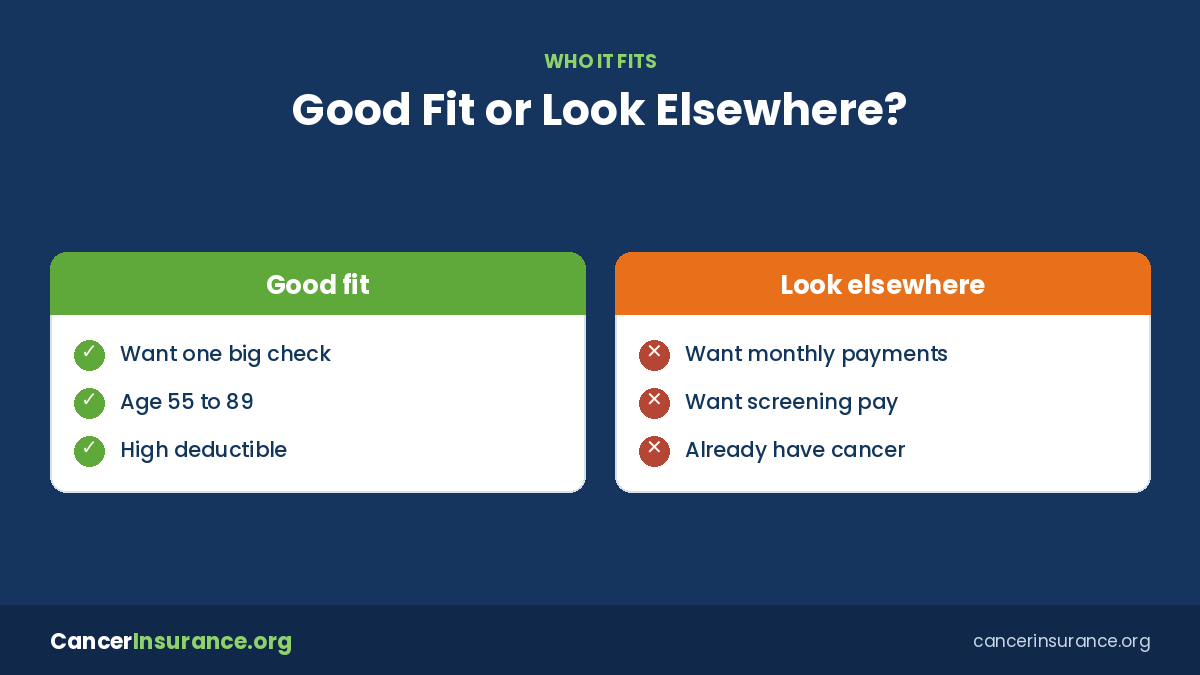
Value comes down to fit. This quick check shows where the policy tends to shine and where another design may serve you better.

Likely worth it if youMay want something else if you
Are 55 to 89 and want lifetime coverageExpect years of treatment and want ongoing payments
Want one large check you can spend freelyWant payments for screenings or each hospital day
Have a high deductible or no paid sick leaveAlready have strong savings and disability income
Want the option to add heart attack and stroke coverageWant benefits for skin cancers other than melanoma

Mutual of Omaha also sells a treatment-based cancer, heart attack and stroke policy in some states. It pays set cash benefits for things like chemotherapy, radiation, surgery and hospital stays over the course of treatment, with issue ages up to 99. If ongoing payments matter more to you than one big check, ask whether that version is offered where you live.

Compare Cancer Insurance Plans

Speak with a licensed insurance agent

1-888-891-0229

Financial Strength and How It Compares

A cancer policy may not pay out for decades, so the insurer’s strength counts. In April 2026, AM Best affirmed a financial strength rating of A+ (Superior) with a stable outlook for Mutual of Omaha and its main subsidiaries.

Versus scheduled plans. Scheduled plans pay smaller amounts as treatment happens. They can pay more in total for long treatment but require more claims.

Versus critical illness. Mutual of Omaha’s critical illness policy covers more conditions but is sold only to age 64 for lifetime coverage.

Versus other lump-sum plans. Benefit ceilings, ages and recurrence rules differ by carrier, so compare the same benefit amount side by side.

For a closer look at the trade-offs, read the pros and cons of the Mutual of Omaha cancer policy or compare it against other options among the 5 best cancer insurance policies.

How to Decide If It Is Worth It for You

Use your own numbers. A few minutes with these steps will tell you more than any review.

1

Find your gap. Add your health plan’s out-of-pocket limit to a few months of income you could lose during treatment.

2

Pick a benefit that fits. Choose an amount close to that gap, then check the premium. Smaller amounts use a shorter application.

3

Choose lifetime or term. Term can cost less while you are working. Lifetime coverage keeps you protected into older age.

4

Read the definitions. Confirm what counts as cancer, the 30-day rule and any state differences in your outline of coverage.

5

Compare one rival quote. Price a similar lump sum from another carrier and a treatment-based plan before you buy.

Good to know: Benefits from a policy you pay for with after-tax dollars are generally not taxed, but rules vary. See are cancer insurance payouts taxable.

Bottom Line

For adults who want a simple, sizable cash payment if cancer strikes, and especially for older buyers who want coverage that lasts for life, a Mutual of Omaha cancer policy is often worth it. If you want payments that continue through long treatment, compare a treatment-based plan before you decide, and remember it supplements your health insurance rather than replacing it.

Get Free Cancer Insurance Quotes

Speak with a licensed insurance agent

1-888-891-0229

Is Mutual of Omaha Cancer Policy Worth It — Frequently Asked Questions

➤ Is Mutual of Omaha cancer insurance worth the money?

It can be if you want one flexible lump sum after a covered diagnosis and you can qualify while healthy. If you want steady payments through long treatment, a scheduled or treatment-based plan may give you more value.

➤ How much does a Mutual of Omaha cancer policy pay?

You choose a lump-sum benefit between $10,000 and $100,000. A covered internal cancer or malignant melanoma pays 100% of that amount directly to you.

➤ What ages can buy Mutual of Omaha cancer insurance?

Lifetime coverage is offered at issue ages 18 to 89, and term coverage at 18 to 54, according to Mutual of Omaha materials. Ages can vary by state.

➤ Does Mutual of Omaha cancer insurance have a waiting period?

Yes. Cancer first diagnosed within 30 days of the policy’s effective date is not covered. Pennsylvania has a different rule that can cover it after two years.

➤ Does the benefit go down as I age?

No. Mutual of Omaha says its cancer policy benefit is not reduced at older ages.

➤ Does Mutual of Omaha cover skin cancer?

The lump-sum policy covers malignant melanoma. Precancerous conditions such as benign moles are not covered, and other skin cancers are not named as covered.

➤ What is Mutual of Omaha’s AM Best rating?

In April 2026, AM Best affirmed an A+ (Superior) financial strength rating with a stable outlook for Mutual of Omaha and its main subsidiaries.

➤ Does Mutual of Omaha cancer insurance replace health insurance?

No. It is a supplemental, limited-benefit policy. You still need employer, Marketplace, Medicare or other major medical coverage to pay for treatment.

Cancer Insurance Quotes

Call a Licensed Agent Now

Compare cancer insurance plans and cash benefits from several insurance companies in one call.

☎ 1-888-891-0229

No obligation to buy

Ready to Compare? Get Free Cancer Insurance Quotes

Speak with a licensed insurance agent

1-888-891-0229

ZRN Health & Financial Services, LLC, a Texas limited liability company