Speak with a licensed insurance agent

1-888-891-0229

Cancer Insurance Pros and Cons: An Honest Look Before You Buy

Updated October 2026

Key Takeaway

The main pros of cancer insurance are cash paid directly to you, help with deductibles and everyday bills, and low premiums when you buy young and healthy. The main cons are that it covers only cancer, has waiting periods and exclusions, and pays nothing if you are never diagnosed.

Cancer insurance gets strong opinions. Some people call it a lifesaver, others call it a waste of money. The truth depends on your health plan, your savings and how a cancer diagnosis would hit your household budget.

This guide lays out the real advantages and drawbacks, compares cancer insurance with other ways to protect yourself, and helps you decide. If you are new to the topic, start with what is cancer insurance. Keep one point in mind throughout: cancer insurance is a supplemental, limited-benefit policy. It pays cash on top of your health plan and does not replace health insurance.
Compare Cancer Insurance Plans

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

How Cancer Insurance Works

Cancer insurance pros and cons out-of-pocket costs a policy can help with

A cancer policy pays fixed cash amounts when you are diagnosed with a covered cancer after your coverage starts. Some pay one lump sum at diagnosis, some pay set amounts as you go through treatment, and some combine both.

The reason people buy it is the gap health insurance leaves behind. Even good coverage has a deductible, coinsurance and an out-of-pocket maximum, and those limits keep rising. Original Medicare has no yearly cap at all on the 20% Part B coinsurance.

Key point: Cancer insurance is not major medical coverage and does not count as health coverage under the Affordable Care Act. It works alongside employer, Marketplace or Medicare coverage, never in place of it.

Cancer Insurance Quotes

Call a Licensed Agent Now

Compare cancer insurance plans and cash benefits from several insurance companies in one call.

☎ 1-888-891-0229

No obligation to buy

The Pros of Cancer Insurance

When it fits your situation, cancer insurance does things your health plan was never built to do.

Cash goes to you. Benefits are paid to you, not your doctors, so you can spend the money on a deductible, rent, groceries or a hotel near treatment.

Pays on top of other coverage. Most policies pay regardless of what your health plan covers, so the two payments do not reduce each other.

Covers non-medical costs. Travel, lodging, child care and lost pay are real cancer costs that health insurance does not touch.

Easy to get while healthy. Many individual policies use a short questionnaire and no exam, and issue ages can run from 18 into the late 80s or 90s.

Two more pluses: stand-alone cancer coverage generally does not affect HSA eligibility, and an individual policy you own stays with you when you change jobs.

The Cons of Cancer Insurance

The drawbacks are just as real. Knowing them up front helps you avoid buying a policy that disappoints you later.

DrawbackWhy it mattersHow to soften it
Covers only cancerHeart attack, stroke and other illnesses get nothingLook at critical illness coverage or a heart attack and stroke rider
Waiting periodA cancer found in roughly the first 30 days is often not coveredBuy early and keep old coverage until the new one is in force
Exclusions and reduced benefitsMost skin cancers and some early-stage cancers may pay little or nothingRead how carcinoma in situ and skin cancer are treated
Premiums with no claimIf you are never diagnosed, the money is spentChoose a benefit level you can afford for years
Hard to get after diagnosisPast cancer can block approvalApply while healthy

General features of cancer policies. Terms vary by carrier, plan and state.

Benefits can also be taxable in some cases, such as when an employer plan is paid with pre-tax dollars.

Cancer Insurance vs. Other Ways to Prepare

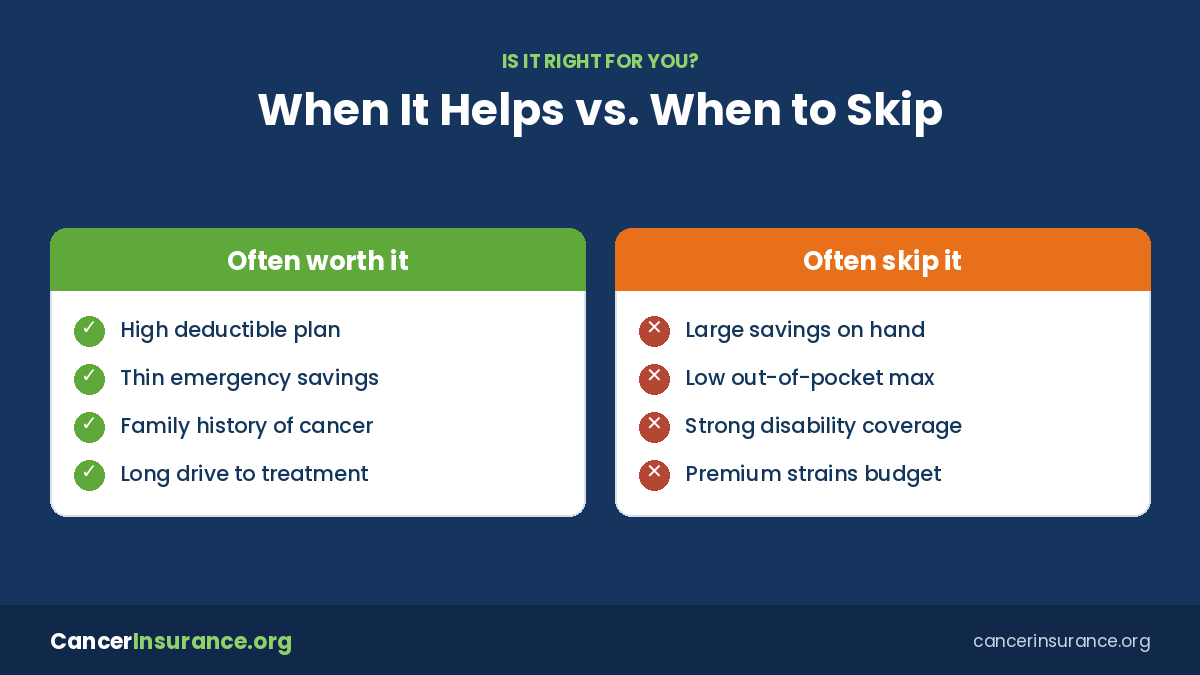
Cancer insurance pros and cons when it is worth it and when to skip it

Cancer insurance is one tool among several. Here is how it compares with the most common alternatives.

OptionWhat it coversMain trade-off
Cancer insuranceCancer only, cash paid to youNarrow coverage, but usually cheaper than broader plans
Critical illness insuranceA list of illnesses, often cancer, heart attack and strokeBroader coverage, often at a higher premium
Emergency savingsAnything at allTakes time to build and can be drained fast
Disability insuranceLost income when you cannot workDoes not help with medical bills or travel

Many people combine two or more of these. Compare features before you buy.

See the side-by-side in cancer insurance vs. critical illness, or read the critical illness insurance pros and cons.

Compare Cancer Insurance Plans

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

What It Costs Compared With What It Can Pay

Price depends on your age, the benefit amount, who is covered, tobacco use and your state. Published employer plans we have reviewed charged roughly $20 to $38 a month for an employee alone. Individual policies are priced by age, so buying younger usually costs less.

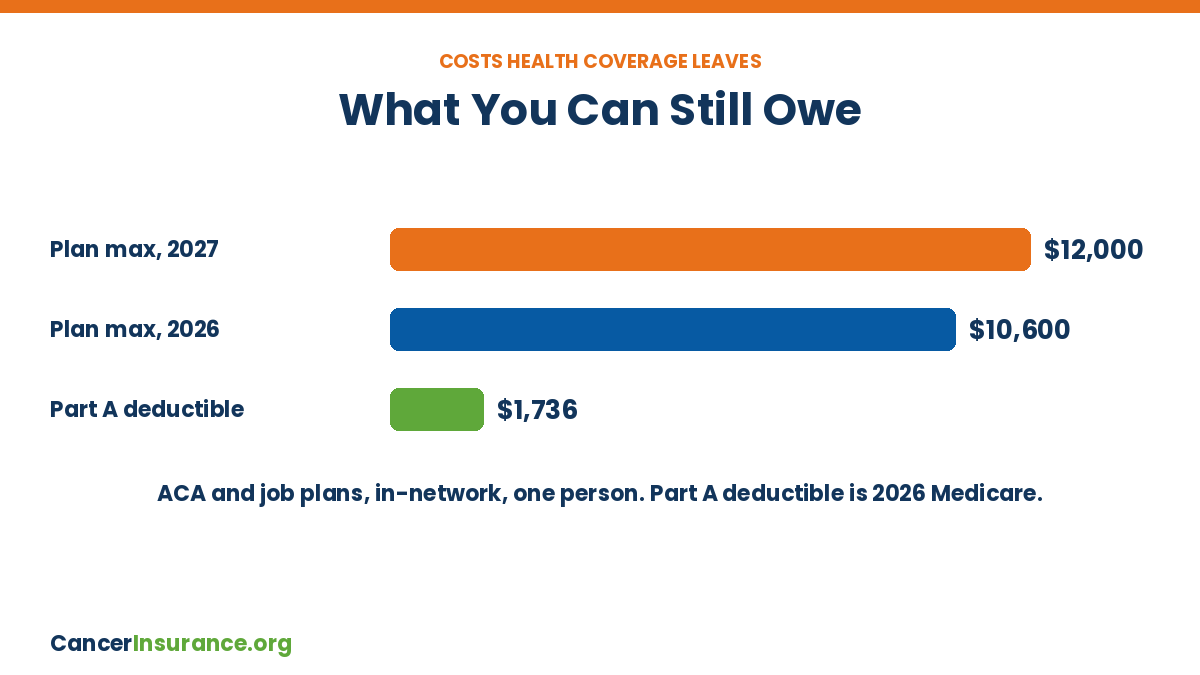
Set that against the bills a diagnosis can bring. For 2027, ACA and employer plans can make one person pay up to $12,000 a year in network, up from $10,600 in 2026. People on Original Medicare without a supplement face a $1,736 Part A hospital deductible in 2026 plus 20% of Part B costs with no cap.

Broker tip: At $20 to $40 a month, a policy costs about $240 to $480 a year. One covered claim can repay many years of premiums, but only if you pick a benefit large enough to matter. Our cancer insurance cost guide breaks down the price.

How to Decide If the Pros Outweigh the Cons

Use these steps to make the call for your own household.

1

Find your gap. Add your health plan’s out-of-pocket maximum to two or three months of household bills.

2

Check what you already have. Look for cancer, critical illness or disability coverage at work or through a spouse.

3

Weigh your risk factors. A family history of cancer, a high deductible or a long drive to a cancer center all tip the scale toward buying.

4

Pick a benefit you can keep. A modest policy you keep for years beats a large one you drop after a year.

5

Compare carriers. Quote the same benefit at two or three companies and read each outline of coverage.

Still unsure? Read is cancer insurance worth it or compare top picks in our 5 best cancer insurance policies guide.

Bottom Line

The biggest pros of cancer insurance are flexible cash paid to you and help with the costs your health plan leaves behind. The biggest cons are narrow coverage, waiting periods and exclusions, and premiums you may never get back. It is a supplemental, limited-benefit policy that makes the most sense for people with high deductibles, thin savings or a family history of cancer.

Get Free Cancer Insurance Quotes

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

Cancer Insurance Pros and Cons — Frequently Asked Questions

➤ What are the main pros of cancer insurance?

It pays cash directly to you, works on top of your health plan, and can cover non-medical costs like travel, lodging and lost pay. Many policies are easy to qualify for while you are healthy.

➤ What are the main cons of cancer insurance?

It covers only cancer, usually has a waiting period of about 30 days, may exclude or reduce benefits for some cancers, and pays nothing if you are never diagnosed.

➤ Is cancer insurance a waste of money?

Not for everyone. It can be valuable if you have a high deductible, little savings or a family history of cancer. It matters less if you have large savings and a low out-of-pocket maximum.

➤ Is cancer insurance better than critical illness insurance?

Cancer insurance is narrower but often cheaper. Critical illness insurance covers several conditions, such as heart attack and stroke, usually for a higher premium.

➤ Does cancer insurance replace health insurance?

No. It is a supplemental, limited-benefit policy that pays cash on top of your health plan. You still need employer, Marketplace, Medicare or other major medical coverage.

➤ Can I buy cancer insurance if I am on Medicare?

Yes. Many carriers sell cancer policies to people on Medicare. The cash can help with deductibles and the 20% Part B coinsurance if you do not have a Medigap plan.

➤ Are cancer insurance benefits taxable?

Benefits are often tax-free when you pay premiums with after-tax money. If an employer plan is paid pre-tax, some benefits may be taxable, so ask a tax professional.

➤ Can I get cancer insurance after a diagnosis?

It is difficult. Most policies ask about past cancer, and a cancer diagnosed before coverage starts is not covered. Buying while healthy is the best approach.

Cancer Insurance Quotes

Call a Licensed Agent Now

Compare cancer insurance plans and cash benefits from several insurance companies in one call.

☎ 1-888-891-0229

No obligation to buy

Ready to Compare? Get Free Cancer Insurance Quotes

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

ZRN Health & Financial Services, LLC, a Texas limited liability company