Speak with a licensed insurance agent

1-888-891-0229

Health Insurance vs Critical Illness: How They Differ and Work Together

Updated October 2026

Key Takeaway

Health insurance pays doctors and hospitals for your care after deductibles and copays. Critical illness insurance is a supplemental policy that pays you a lump sum when you are diagnosed with a covered condition, so it adds cash on top of your health plan but never replaces it.

Health insurance and critical illness insurance both show up when a serious diagnosis hits, but they do very different jobs. One pays for your medical care. The other puts money in your hands so you can handle everything else that comes with being sick.

This guide compares health insurance vs critical illness coverage side by side, shows where the gaps are for employer, ACA Marketplace and Medicare members, and explains how to decide if a lump-sum plan belongs next to your health plan. For the basics of the product itself, start with our critical illness insurance overview.

Compare Critical Illness and Cancer Plans

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

What Health Insurance and Critical Illness Insurance Each Do

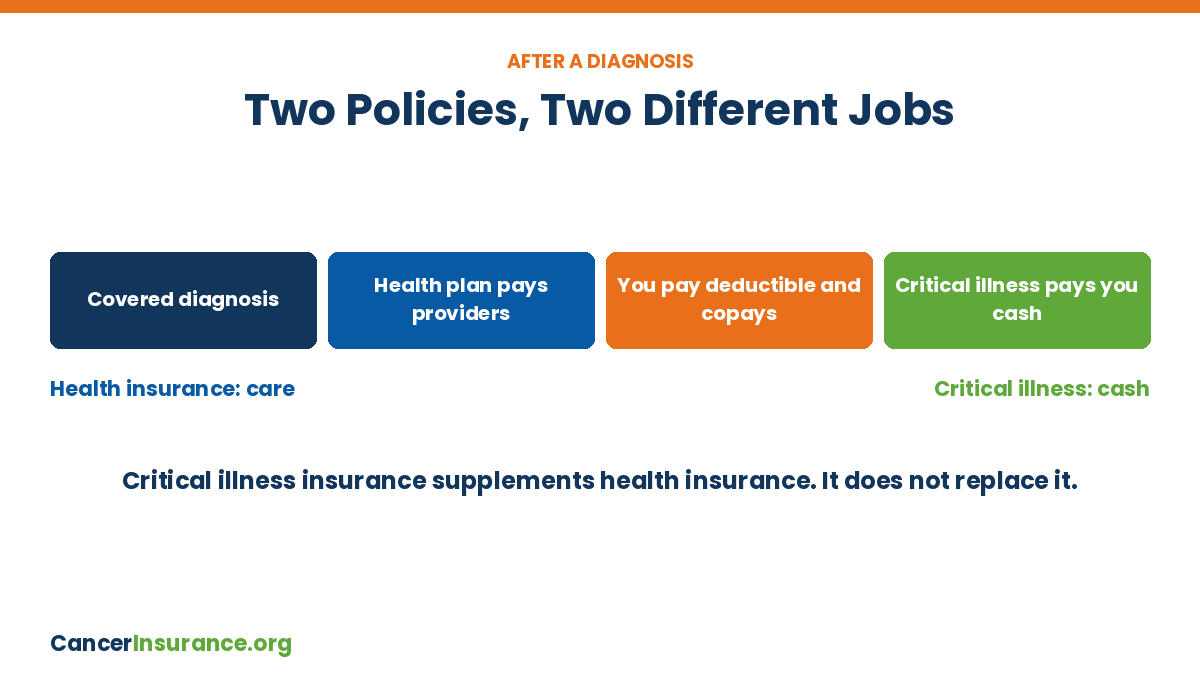
Health insurance vs critical illness claim flow after a serious diagnosis

Health insurance is your main medical coverage. It might come from an employer, the ACA Marketplace, Medicare or Medicaid. When you see a doctor, get a scan or stay in the hospital, the plan pays its share of the bill, usually straight to the provider, after you meet your deductible, copays and coinsurance.

Critical illness insurance works on a different idea. It is a supplemental, limited-benefit policy. When you are diagnosed with a condition the policy lists, it pays a set cash amount to you. It does not look at your medical bills and it does not care what your health plan already paid.

Health insurance pays for care. It covers doctor visits, hospital stays, surgery, drugs and preventive care, within the plan’s rules and network.

Critical illness pays for life. The lump sum can go toward rent, groceries, travel to a treatment center, child care or a lost paycheck.

One is required coverage, one is extra. Critical illness plans are excepted benefits. They are not minimum essential coverage and cannot stand in for a health plan.

Good to know: Covered conditions vary by policy. Many critical illness plans list conditions such as invasive cancer, heart attack, stroke, kidney failure and major organ transplant, but each policy defines them in its own words.

Cancer Insurance Quotes

Call a Licensed Agent Now

Compare cancer insurance plans and cash benefits from several insurance companies in one call.

☎ 1-888-891-0229

No obligation to buy

Health Insurance vs Critical Illness: Side-by-Side Comparison

The easiest way to see the difference is to line the two up feature by feature. Read across each row to see who pays, who gets the money and what you are responsible for.

FeatureHealth insuranceCritical illness insurance
Main jobPays for medical carePays cash after a covered diagnosis
Who gets paidUsually the doctor or hospitalYou, the policyholder
How much it paysA share of each bill after cost sharingA set lump sum you choose when you buy
Deductible and copaysYes, until you hit the out-of-pocket maximumNo deductible on the lump sum
NetworksOften limited to in-network providersNo network; any doctor can diagnose
Counts as required coverageYesNo, it is a supplement
Paid on top of other coverageCoordinates with other plansPays regardless of other insurance

General comparison. Exact terms depend on the specific health plan and critical illness policy.

Cancer-only coverage follows the same cash idea but focuses on one disease. Our guide to cancer insurance versus critical illness insurance breaks down that choice.

The Costs Health Insurance Leaves Behind

Even good health insurance leaves you paying part of the bill. A serious illness can also bring costs a health plan was never built to touch, like a spouse taking unpaid time off or a long drive to a cancer center.

Deductibles and coinsurance. Employer and Marketplace plans make you pay a share of costs until you reach your yearly out-of-pocket maximum.

Medicare cost sharing. In 2026, Original Medicare has a $1,736 Part A deductible per benefit period and a $283 Part B deductible, plus 20% Part B coinsurance with no yearly cap unless you have other coverage.

Non-medical bills. Rent, utilities, car payments and groceries keep coming even when you cannot work.

Travel and lodging. Trips to a specialist, hotel stays and meals near a treatment center are rarely covered by a health plan.

These are the gaps a lump sum is meant to fill. Because the money is paid to you, you decide where it goes first.

How Out-of-Pocket Limits Shape the Decision

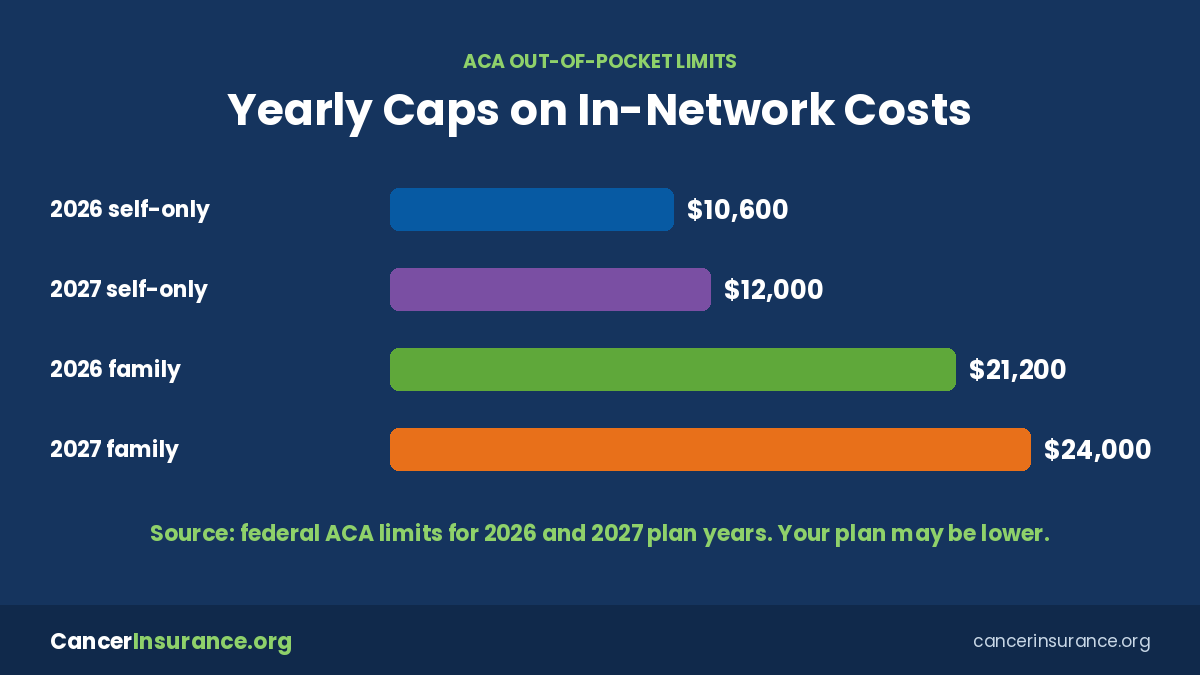
ACA out-of-pocket maximum limits for 2026 and 2027 when comparing health insurance vs critical illness

ACA-compliant employer and Marketplace plans cap what you pay for covered in-network care each year. That cap is rising. For 2026 it is $10,600 for self-only coverage and $21,200 for a family. Federal limits for 2027 plan years are set at $12,000 and $24,000.

Your own plan’s limit may be lower, so check your plan documents. Still, the number gives you a useful target. If you could not pay your plan’s full out-of-pocket maximum from savings, a critical illness benefit sized near that amount can keep a big diagnosis from turning into debt.

Broker tip: Add up your plan’s out-of-pocket maximum plus two or three months of household bills. That total is a simple starting point for choosing a lump-sum amount. See how premiums change by benefit size on our critical illness insurance cost page.

Compare Critical Illness and Cancer Plans

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

Who Should Add Critical Illness Coverage to Health Insurance

A critical illness plan is not for everyone. It earns its keep when the gap between your health plan and your savings is large.

High-deductible plan members. If your deductible is several thousand dollars, a lump sum can cover it the first month.

Single-income households. When one paycheck pays the bills, a diagnosis that stops work hits hard and fast.

Medicare members with gaps. People on Original Medicare without a supplement, or on Medicare Advantage with high copays, may face large shares of treatment costs.

Those with a family history. If heart disease, stroke or cancer runs in your family, coverage bought while you are healthy can be easier to get.

If you already have strong savings, a low-deductible plan and paid sick leave, the extra premium may not be worth it. Our guide on whether critical illness insurance is worth it walks through that test.

How to Pair Critical Illness Insurance With Your Health Plan

Think of health insurance as the base layer and critical illness coverage as the cash layer on top. Follow these steps so the two fit together.

1

Keep your health plan first. Never drop major medical coverage to pay for a critical illness policy. It does not pay your doctors.

2

Know your gap. Find your deductible, out-of-pocket maximum and how much sick pay or savings you have.

3

Read the covered conditions. Check which illnesses qualify, how each is defined and whether early-stage cancer pays a reduced amount.

4

Check the waiting period and health questions. Many policies have a waiting period and limits on pre-existing conditions. Some group plans offer guaranteed issue during enrollment.

5

Compare more than one company. Look at lump-sum size, premiums and recurrence rules side by side before you sign.

When you are ready, see how a critical illness lump sum payment works, or browse cancer insurance options built for the same purpose.

Bottom Line

Health insurance pays for your medical care, while critical illness insurance pays you cash after a covered diagnosis. They are not competitors. Keep your health plan as the foundation, and add a lump-sum policy only if the gap between your out-of-pocket costs and your savings is more than you could handle.

Get Free Critical Illness Insurance Quotes

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

Health Insurance vs Critical Illness — Frequently Asked Questions

➤ What is the main difference between health insurance and critical illness insurance?

Health insurance pays a share of your medical bills, usually directly to providers. Critical illness insurance pays a set lump sum to you after a covered diagnosis, and you can use it for any expense.

➤ Can critical illness insurance replace health insurance?

No. Critical illness insurance is a supplemental, limited-benefit policy and an excepted benefit. It is not minimum essential coverage, and it does not pay for doctor visits, hospital care or prescriptions.

➤ Does critical illness insurance pay if my health plan already paid?

Yes. A critical illness policy pays its stated benefit regardless of what your health insurance pays, so the cash comes on top of your other coverage.

➤ Does critical illness insurance have a deductible?

The lump sum itself usually has no deductible. If your claim is approved, you receive the benefit amount stated in the policy, minus nothing for cost sharing.

➤ What illnesses does critical illness insurance cover?

It depends on the policy. Many plans list conditions such as invasive cancer, heart attack, stroke, kidney failure and major organ transplant, each with its own definition. Read the policy’s list before you buy.

➤ What are the ACA out-of-pocket limits for 2027?

Federal limits for 2027 plan years are $12,000 for self-only coverage and $24,000 for family coverage, up from $10,600 and $21,200 in 2026. Your plan’s limit may be lower.

➤ Can I get critical illness insurance with Medicare?

Yes. Many people on Original Medicare or Medicare Advantage buy a critical illness or cancer policy to help with deductibles, coinsurance, copays and non-medical costs. It pays on top of Medicare and does not replace it.

➤ Is critical illness insurance worth it if I have good health insurance?

It may not be if you have a low deductible, solid savings and paid sick leave. It tends to make more sense with a high-deductible plan, a single income or limited savings.
Cancer Insurance Quotes

Call a Licensed Agent Now

Compare cancer insurance plans and cash benefits from several insurance companies in one call.

☎ 1-888-891-0229

No obligation to buy

Ready to Compare? Get Free Cancer Insurance Quotes

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

ZRN Health & Financial Services, LLC, a Texas limited liability company