Updated October 2026
Key Takeaway
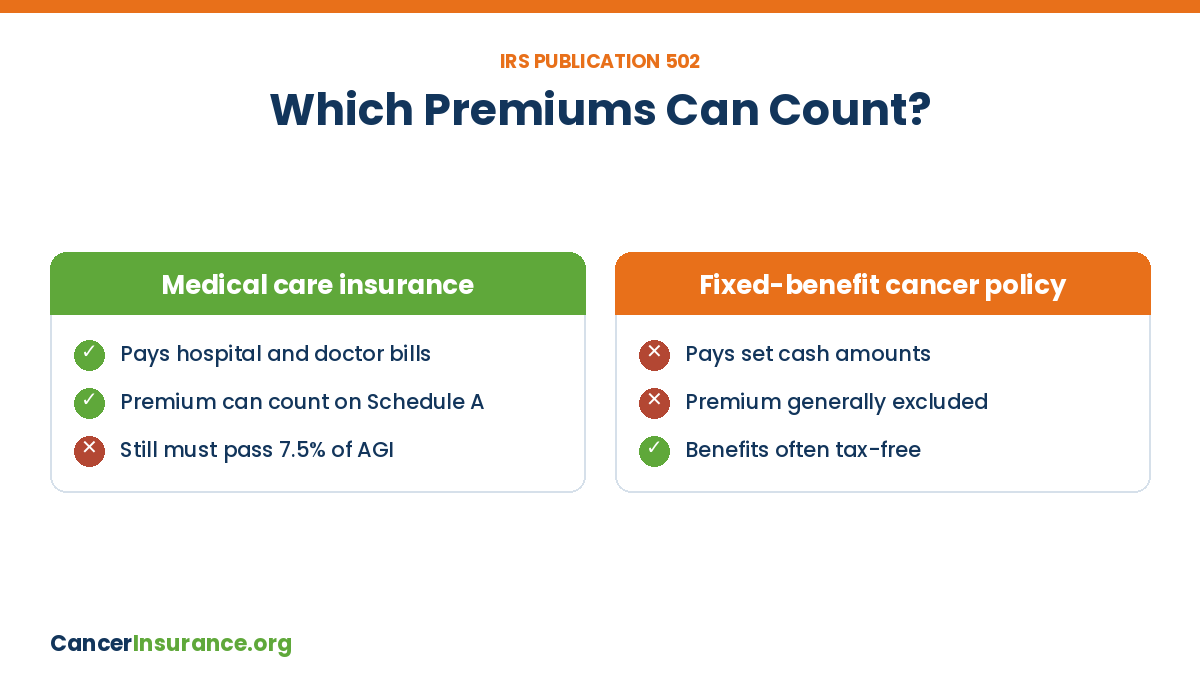
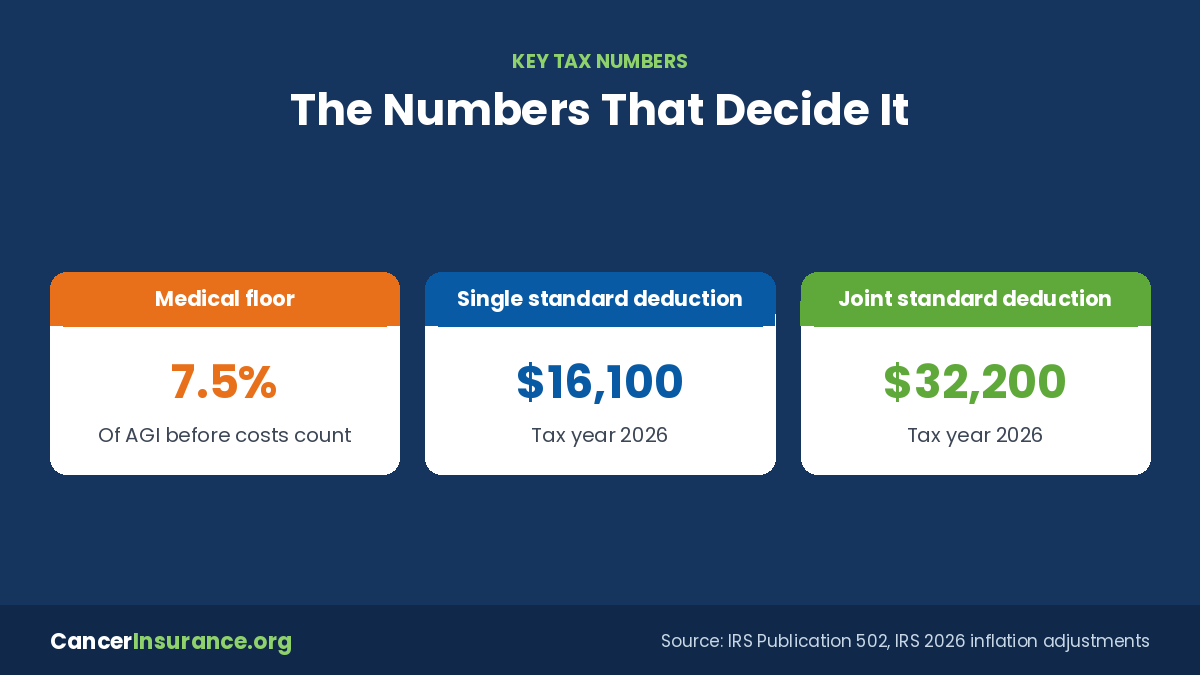
Usually not. Most cancer policies pay fixed cash amounts rather than medical bills, and IRS Publication 502 does not let you count premiums for policies that pay a guaranteed amount as medical expenses. Even when a premium could count, you must itemize and your total medical costs must top 7.5% of your income.
Cancer insurance premiums can add up to a few hundred dollars a year or more, so it is fair to ask whether the IRS gives anything back. The short answer is that for most people it does not, but the reasons matter, and there are a few setups where the tax picture changes.
This guide explains the IRS rule on insurance premiums, why most cancer policies fall outside it, the itemizing test, and what changes for workers who pay through payroll, self-employed people and HSA owners. This is general information, not tax advice. If you are new to the product, start with what cancer insurance is: a supplemental, limited-benefit policy that pays cash on top of health insurance and does not replace it.