Speak with a licensed insurance agent

1-888-891-0229

Lump Sum Cancer Insurance: How a One-Time Cancer Payout Works

Updated October 2026

Key Takeaway

Lump sum cancer insurance pays one cash benefit, such as $10,000 or $25,000, when you are first diagnosed with a covered cancer. You can spend the money on anything, but it is a supplemental, limited-benefit policy and does not replace health insurance.

A cancer diagnosis brings bills right away: the deductible, scans, time off work and travel to a cancer center. A lump sum cancer policy is built for that moment. Instead of paying small amounts as each treatment happens, it sends you one check soon after a covered diagnosis.

This guide explains how the lump sum design works, how it compares with treatment-based plans, the fine print that can shrink a payout and how to choose a benefit amount. For a broader view of the market, see our types of cancer insurance plans guide or start at our cancer insurance home page.
Compare Lump Sum Cancer Insurance Plans

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

How Lump Sum Cancer Insurance Works

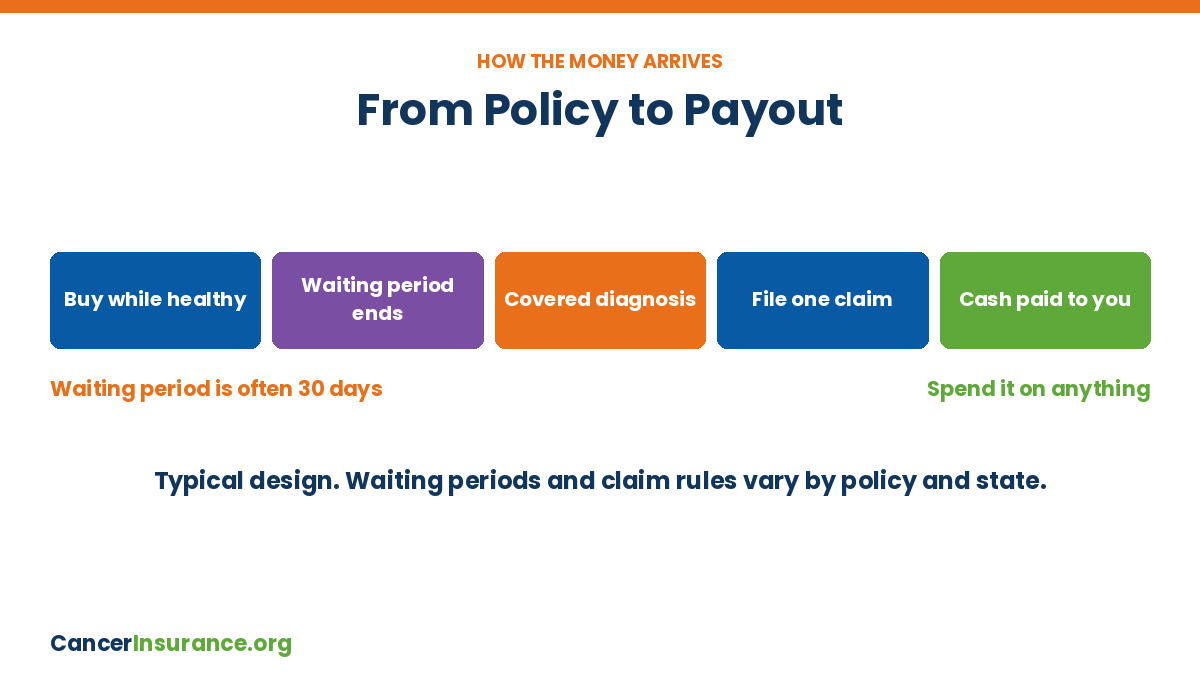
Lump sum cancer insurance timeline from buying a policy to receiving the cash payout

You choose a benefit amount when you buy the policy. If you are later diagnosed with a covered cancer after any waiting period, the insurer pays that amount to you in one payment. The amount does not depend on your medical bills or on what your health plan paid.

Set when you buy. You pick the benefit amount up front, often in steps of a few thousand dollars, and your premium is based on it plus your age and tobacco use.

Paid once, in full. After a covered diagnosis and any waiting period, the whole amount is paid in a single check.

Not tied to bills. The payout does not shrink because your health plan paid most of the cost.

One claim. You usually send a pathology report and a claim form, then wait for approval.

Good to know: Because the money is yours, you can use it for a deductible, a hotel near the cancer center, rent, groceries or child care. Nothing ties it to a medical bill.

Cancer Insurance Quotes

Call a Licensed Agent Now

Compare cancer insurance plans and cash benefits from several insurance companies in one call.

☎ 1-888-891-0229

No obligation to buy

Lump Sum vs. Treatment-Based Cancer Plans

Cancer policies come in two main designs. Many carriers let you combine them with riders.

The trade-off is timing. A lump sum puts the most money in your hands in the first weeks after diagnosis, when the deductible and the first scans hit. A treatment-based plan pays less at first but can keep paying for months of chemo, radiation and hospital stays. People who expect long treatment, or who already have a solid emergency fund, sometimes prefer the second design or a mix of both.

FeatureLump sum planTreatment-based plan
When it paysOnce, at diagnosisAs each treatment happens
How muchThe amount you choseSet amounts per day, week or procedure
Number of claimsUsually oneMany, through treatment
Best forFast cash for early costsLong or repeated treatment
Main riskLong treatment can outlast the checkLess cash in the first weeks

Many treatment-based plans offer a diagnosis rider that adds a smaller lump sum.

If you want to see how scheduled benefits add up, our page on cancer treatment insurance covers that design.

Sample Lump Sum Benefit Ranges

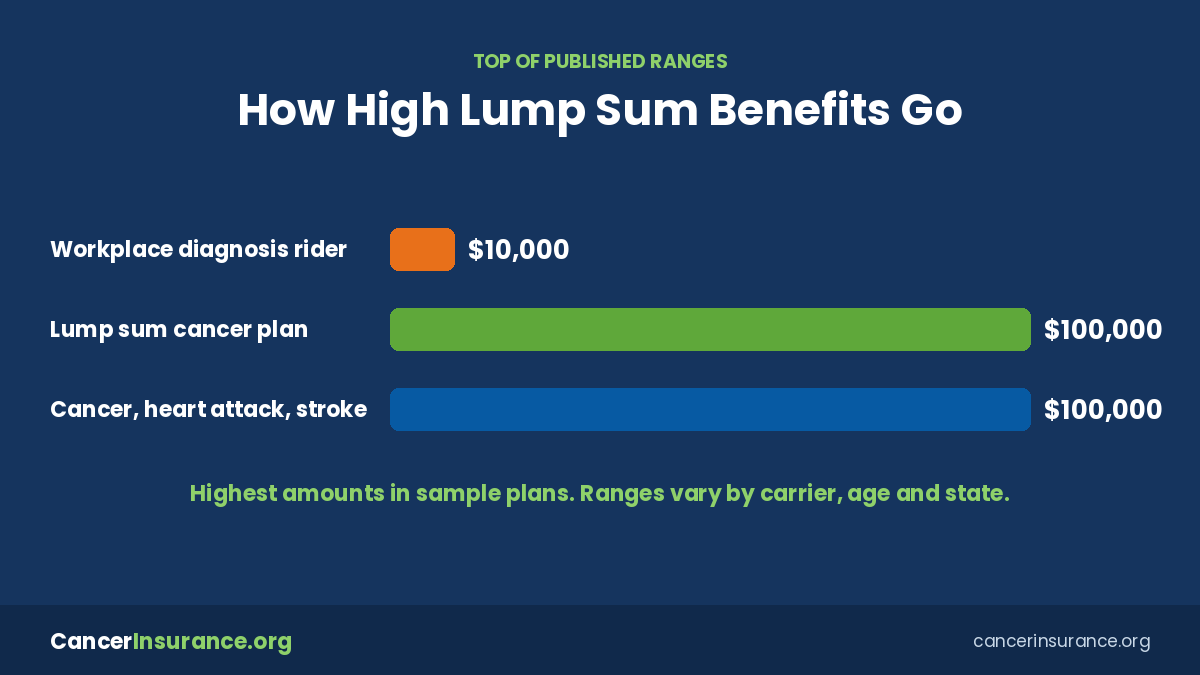
Benefit ranges vary a lot by carrier and state. Here are examples from carriers’ own published plan details.

HealthSpring Lump Sum Cancer. Benefit amounts from $5,000 to $100,000 for issue ages 18 to 99. Not sold in Idaho, New Mexico, New York, Virginia or Wyoming.

Mutual of Omaha Cancer, Heart Attack and Stroke. Pays $10,000 to $100,000 at diagnosis for issue ages 18 to 89, with limited underwriting. Also covers heart attack and stroke.

Workplace diagnosis riders. Employer plans such as Colonial Life’s Cancer Assist offer an optional diagnosis rider that pays $1,000 to $10,000.

Amounts, ages and riders differ by state, so always read the outline of coverage for where you live. Our best lump sum cancer insurance page compares carriers side by side.

Fine Print That Can Reduce the Payout

Lump sum cancer insurance maximum benefit amounts by plan type

A lump sum policy is simple, but the definitions decide whether you get the full check, part of it or nothing.

Waiting period. A cancer first diagnosed in the first 30 days or so is often not covered at all. Mutual of Omaha, for example, does not pay for cancer first diagnosed within 30 days of the effective date.

What counts as cancer. Many policies pay in full for internal cancer or malignant melanoma but exclude pre-cancerous conditions. Some pay a smaller share for early-stage or in-situ cancers, and many exclude most skin cancers.

Pre-existing cancer. A cancer diagnosed before the policy started is not covered.

Recurrence. The base benefit usually pays once. Some carriers sell a recurrence rider. HealthSpring’s pays up to an extra 100% for a later diagnosis after two years with no treatment.

Broker tip: Ask each carrier what share it pays for carcinoma in situ and skin cancer. Two policies with the same headline amount can pay very different checks for an early-stage diagnosis.

Compare Lump Sum Cancer Insurance Plans

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

How Much Lump Sum Coverage Do You Need?

A good starting point is the money you would have to find in the first year of treatment.

1

Start with your out-of-pocket maximum. For a 2026 ACA Marketplace plan, that can be up to $10,600 per person. Check your employer plan or Medicare coverage for your own number.

2

Add lost income. Estimate how many weeks of pay you or a caregiver might miss.

3

Add travel and home costs. Include gas, hotel nights, meals and child care if the nearest cancer center is far away.

4

Subtract your savings cushion. Choose a benefit that covers the gap your savings and disability coverage would not.

Our guide to calculating cancer insurance coverage needs walks through the math with examples.

Example: Say your health plan’s out-of-pocket maximum is $8,000, you expect to miss six weeks of pay worth $6,000, and travel would cost about $2,000. That is a $16,000 gap. With $6,000 in savings, a $10,000 lump sum would cover the rest. This is a made-up example for illustration only.

Who a Lump Sum Policy Fits Best

Lump sum coverage works well for people who want fast, flexible cash and do not want to file claim after claim.

Good fit. People with high-deductible employer or ACA plans who would struggle to cover the out-of-pocket maximum.

Good fit. Self-employed workers and single-income families who would lose pay during treatment.

Good fit. People on Original Medicare without a Medigap plan, who face 20% Part B coinsurance with no yearly cap.

Weaker fit. People with large savings and a low out-of-pocket limit, or anyone who wants benefits that keep paying through long treatment.

One more point: if a workplace lump sum plan is paid with pre-tax dollars, the benefit is generally taxable. Policies you pay for with after-tax money generally pay tax-free. A tax professional can confirm your setup.

Bottom Line

Lump sum cancer insurance sends one cash payment after a covered diagnosis, which makes it easy to cover early costs and lost pay. Read how the policy defines cancer, the waiting period and any recurrence rider, and size the benefit to your real first-year gap. Remember it adds to health insurance and never replaces it.

Get Free Lump Sum Cancer Insurance Quotes

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

Lump Sum Cancer Insurance — Frequently Asked Questions

➤ What is lump sum cancer insurance?

It is a supplemental policy that pays one cash benefit when you are first diagnosed with a covered cancer. You choose the amount when you buy, and the money is paid to you to spend as you wish.

➤ How much does a lump sum cancer policy pay?

It pays the amount you chose. Published ranges include $5,000 to $100,000 for HealthSpring and $10,000 to $100,000 for Mutual of Omaha’s cancer, heart attack and stroke plan.

➤ Does lump sum cancer insurance pay more than once?

Usually the base benefit pays once. Some carriers sell a recurrence rider that pays again for a later cancer if you have gone a set time, such as two years, without treatment.

➤ Does it pay for skin cancer?

Many lump sum policies exclude most skin cancers or pay a smaller amount. Malignant melanoma is often treated as a covered cancer. Check the definitions in your policy.

➤ Is there a waiting period?

Most policies have one, often 30 days. A cancer first diagnosed during that time is usually not covered.

➤ Is a lump sum cancer payout taxable?

If you paid the premium with after-tax money, the benefit is generally not taxable. If an employer paid or you paid pre-tax through a cafeteria plan, the benefit is generally taxable.

➤ Can I get lump sum cancer insurance after a diagnosis?

Not for a cancer you already have. Most policies exclude cancers diagnosed before coverage starts, and many ask about past cancer on the application.

➤ Does lump sum cancer insurance replace health insurance?

No. It is a supplemental, limited-benefit policy that pays cash on top of your employer plan, ACA plan or Medicare. It does not pay your doctors or hospital.

Cancer Insurance Quotes

Call a Licensed Agent Now

Compare cancer insurance plans and cash benefits from several insurance companies in one call.

☎ 1-888-891-0229

No obligation to buy

Ready to Compare? Get Free Cancer Insurance Quotes

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

ZRN Health & Financial Services, LLC, a Texas limited liability company