➤ What cancer plans does ManhattanLife sell?
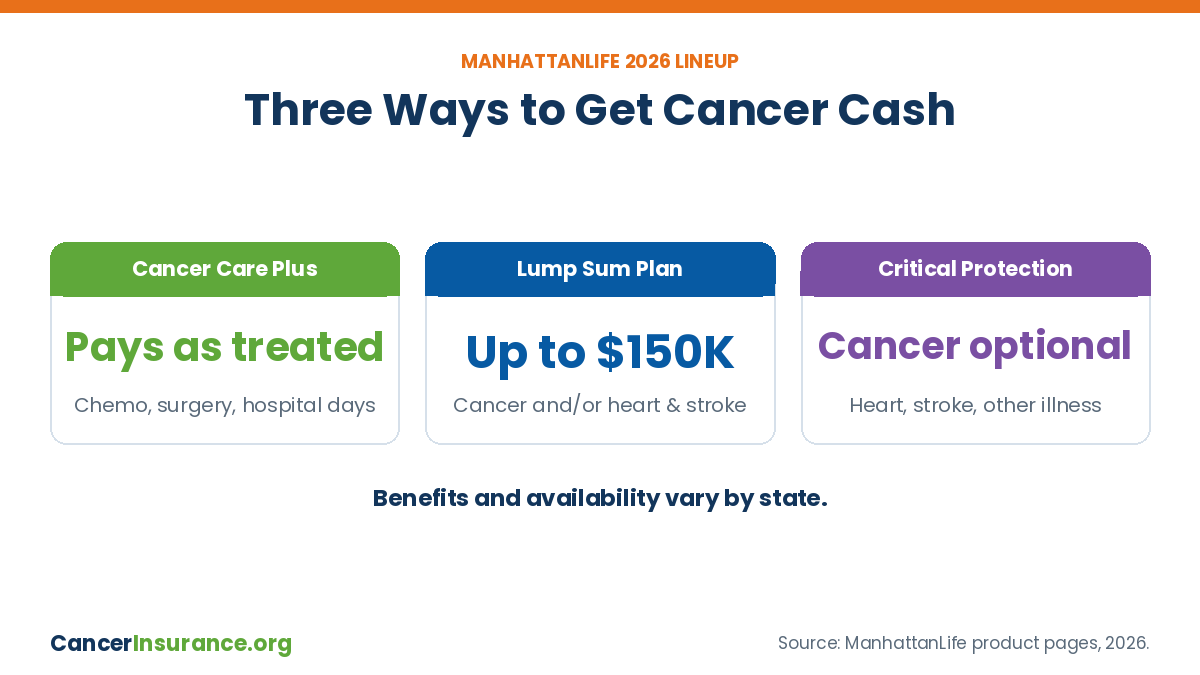
Its current cancer lineup includes Cancer Care Plus, a lump sum Cancer and/or Heart Attack and Stroke policy, and Critical Protection and Recovery with an optional cancer benefit. Availability varies by state.
➤ Did ManhattanLife discontinue a cancer plan?
Yes. ManhattanLife announced that its Cancer First Occurrence Benefit product would no longer be sold after February 1, 2026. Existing policies stay in force as long as premiums are paid.
➤ Does Manhattan Life cancer insurance pay a lump sum?
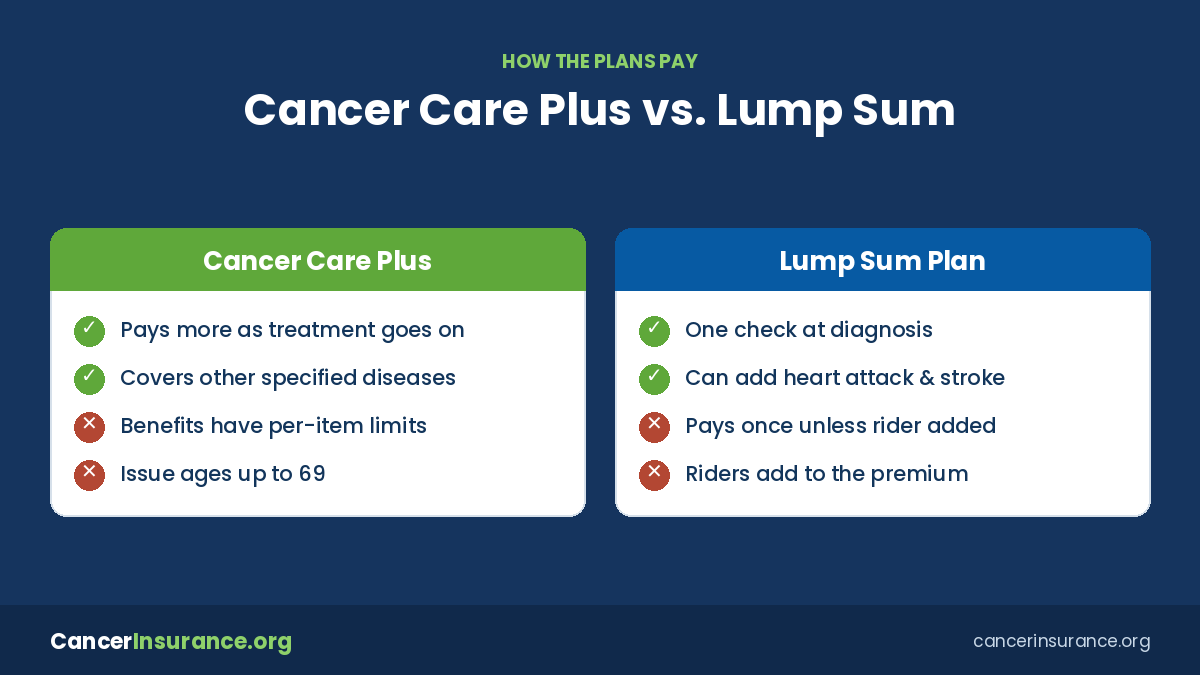
The Cancer and/or Heart Attack and Stroke policy pays a lump sum after a covered diagnosis, up to $150,000 when cancer and heart coverage are combined. Cancer Care Plus mainly pays set amounts for treatments, with an optional one-time first occurrence benefit.
➤ What is ManhattanLife’s AM Best rating?
In January 2022, AM Best upgraded the Manhattan Insurance Group companies to a financial strength rating of B++ (Good) with a stable outlook. Check the current rating for the company named on your policy.
➤ Who can buy Manhattan Life cancer insurance?
Issue ages depend on the plan. A Cancer Care Plus brochure lists ages 18 to 69, and a lump sum brochure shows rates for ages 20 to 84. Health questions and state rules also apply.
➤ Does Manhattan Life cancer insurance replace health insurance?
No. It is a supplemental, limited-benefit policy that pays set cash amounts. You still need health insurance, Medicare or another major medical plan to pay your treatment bills.
➤ Is there a waiting period?
Yes. Cancer diagnosed during the waiting period is not covered, and the heart attack and stroke part of the lump sum plan has a 30-day waiting period. Ask your agent for the cancer waiting period in your state.
➤ Who pays the benefit, me or the hospital?
Benefits are paid to you. You can use the money for medical bills, travel to treatment, household bills or lost income.