Speak with a licensed insurance agent

1-888-891-0229

Supplemental Cancer Insurance Companies: How to Vet and Compare Them

Updated October 2026

Key Takeaway

Supplemental cancer insurance companies include Aflac, Colonial Life, Mutual of Omaha, Physicians Mutual, Washington National and ManhattanLife. The best choice depends on whether you buy at work or on your own, how the plan pays, and the company’s financial strength and claims record.

Dozens of companies sell supplemental cancer insurance, and many of their plans look alike at first glance. The real differences show up in how a company designs its benefits, how it handles claims, how it sells, and how financially strong it is.

This guide gives you a simple way to vet any company, with examples from well-known carriers. For a list of companies with ratings, see our cancer insurance providers page. Keep one rule in mind with every company: supplemental cancer insurance is limited-benefit coverage that pays cash on top of your health plan. It does not replace health insurance.
Compare Cancer Insurance Plans

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

The Main Types of Supplemental Cancer Insurance Companies

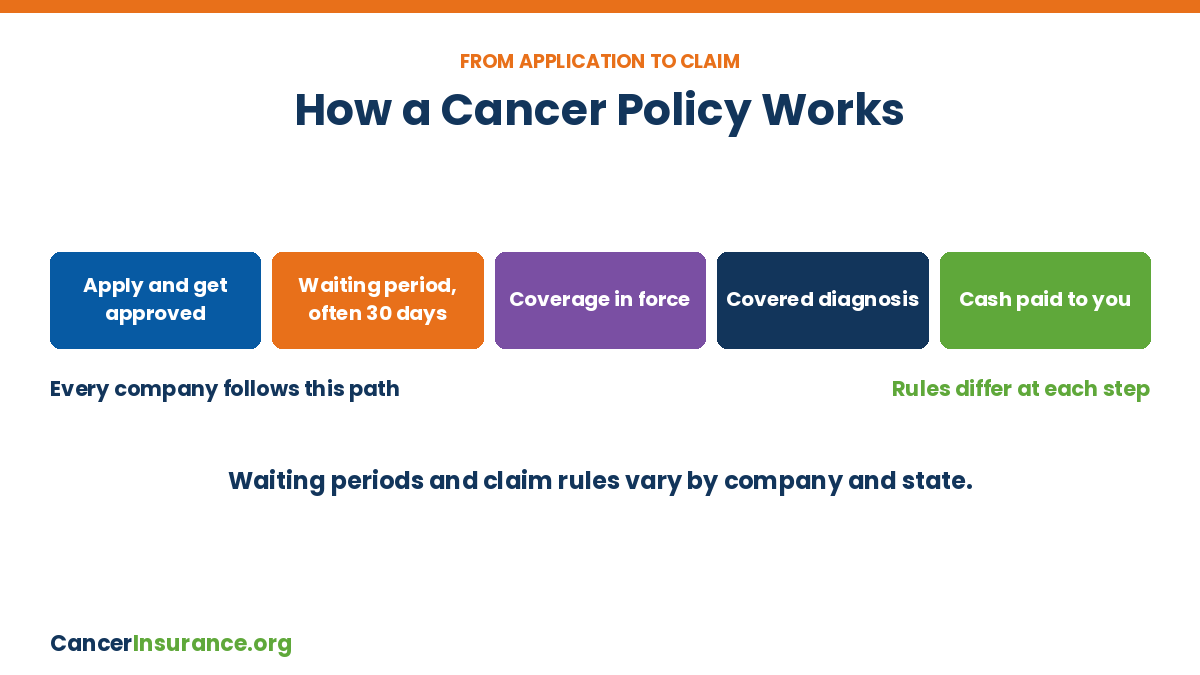
How supplemental cancer insurance companies handle a policy from application to claim payment

Companies that sell cancer coverage tend to fall into a few groups. Knowing which group a company is in tells you a lot about how you will buy from it and how its plans are built.

Workplace specialists. Companies such as Aflac and Colonial Life sell many of their plans through employers, often with payroll deduction and simpler enrollment.

Individual-market carriers. Companies such as Mutual of Omaha and Physicians Mutual sell directly to individuals and families, including people on Medicare.

Agent-sold supplemental insurers. Companies such as ManhattanLife and Washington National sell mainly through licensed agents who can explain benefit schedules and riders.

Group benefits carriers. Large benefits companies such as Voya often offer cancer protection inside critical illness plans sold to employers.

Cancer Insurance Quotes

Call a Licensed Agent Now

Compare cancer insurance plans and cash benefits from several insurance companies in one call.

☎ 1-888-891-0229

No obligation to buy

Supplemental Cancer Insurance Companies Compared

Here is how several familiar companies differ on rating and plan style. Ratings are AM Best financial strength ratings from the most recent announcement we found.

CompanyAM Best ratingHow its plans are often built
AflacA+ (Superior), Sept. 2025Diagnosis and treatment benefits; sold at work and individually
Colonial LifeA (Excellent), Sept. 2025Mostly sold through employers
Mutual of OmahaA+ (Superior), March 2025Lump sum of $10,000 to $100,000 for cancer, or cancer plus heart attack and stroke
Physicians MutualA+ (Superior), Nov. 2025 upgradeIndividual plans sold direct and through agents
Washington NationalA (Excellent), Feb. 2025Agent-sold supplemental health plans; a CNO Financial company
ManhattanLifeB++ (Good), Jan. 2022 upgradeCancer Care Plus benefit schedule or a lump sum plan up to $150,000 combined

Sources: AM Best announcements and company materials. Ratings can change and plans vary by state. Check the rating of the company named on your policy.

Notice that the brand you know is not always the company on the contract. Aflac plans are issued by American Family Life Assurance Company of Columbus, and ManhattanLife plans may be issued by one of several affiliated insurers. Plan names, benefit amounts and riders also change from state to state, so a plan you read about online may look different in your state. Always confirm details with a quote for your ZIP code.

What to Compare Beyond the Premium

Two policies with the same monthly price can pay very different amounts after a diagnosis. Look at these points side by side.

1

How benefits pay. Lump sum plans pay one check at diagnosis. Benefit-schedule plans pay set amounts for treatment. Some do both.

2

What counts as cancer. Check how the policy pays for carcinoma in situ and skin cancer. Many pay a reduced amount or exclude them.

3

Waiting period and pre-existing rules. Many plans use a 30-day waiting period. Aflac’s individual cancer policy and Mutual of Omaha’s lump sum plan both exclude cancer diagnosed in the first 30 days.

4

Recurrence and renewability. Ask whether the plan pays again if cancer returns and whether it is guaranteed renewable.

Broker tip: Ask each company for the outline of coverage, not just the brochure. The outline lists definitions, limits and exclusions in one place, which makes side-by-side comparison much easier.

Buying at Work or on Your Own

Supplemental cancer insurance companies at work compared with buying an individual policy

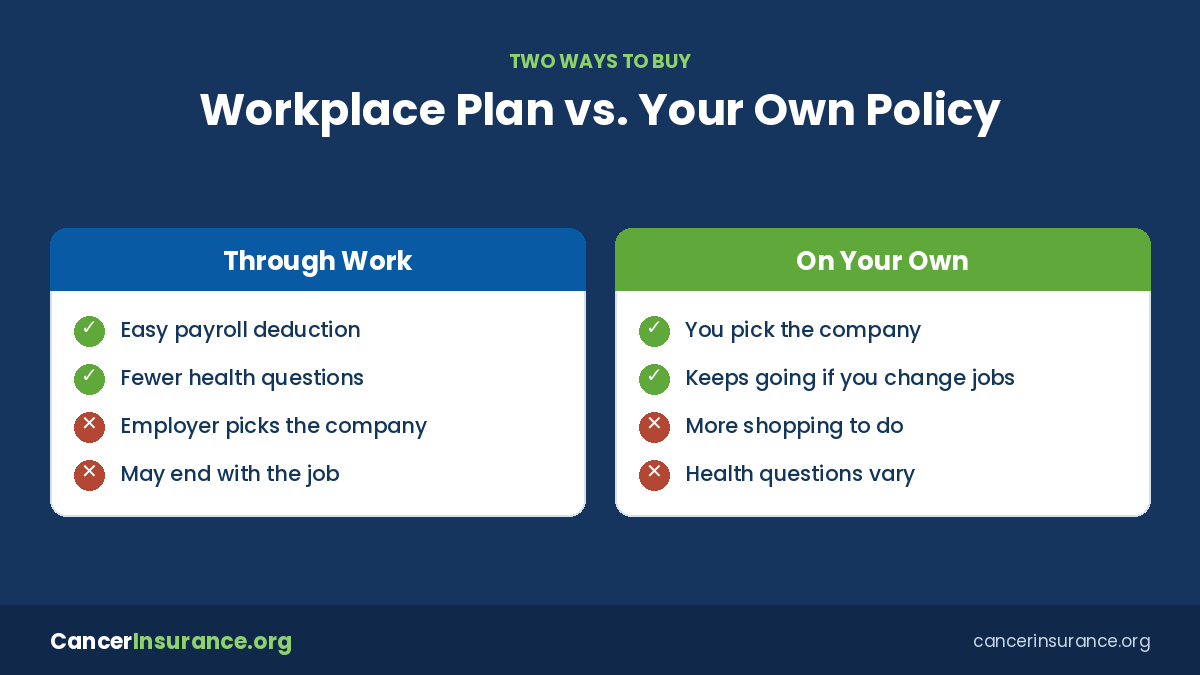
Where you buy shapes which companies you can choose from and how the plan behaves if your life changes. At work, your employer picks the company, premiums come out of your paycheck, and open enrollment often asks few or no health questions. On your own, you pick the company and pay by bank draft or card, and health questions vary by plan.

Ask about portability: Some workplace cancer plans let you keep coverage if you leave the job, often by paying the company directly. Others end with your employment. Ask before you count on a work plan as your only cancer coverage.

Medicare and ACA readers buy on their own, so they can compare many companies at once. Employer plan members can add an individual policy if the workplace plan is too small.

Compare Cancer Insurance Plans

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

How to Check a Company's Strength and Service

A cancer policy is a promise that may not be tested for years. Make sure the company behind it will be around and will treat claims fairly.

Financial strength rating. AM Best grades insurers on their ability to pay claims. Ratings in the A range are considered Excellent or Superior; B++ is Good.

The exact insurer name. Many brands use more than one insurance company. The rating that matters is for the company named on your policy.

Complaint records. Your state insurance department and the NAIC’s online consumer tool show complaint data for licensed insurers.

State license. Make sure the company and the agent are licensed in your state before you apply.

Service matters too. Ask how claims are filed, whether you can submit them online, and what documents the company needs, such as a pathology report. A company that pays claims quickly and clearly is worth a small difference in price.

How to Choose a Supplemental Cancer Insurance Company

Put it all together with a short process that works for employer, ACA and Medicare shoppers alike.

1

Start with your gap. Check your health plan’s out-of-pocket maximum and how long you could go without pay.

2

Pick a payment style. Decide between a lump sum, treatment benefits or both. Our guide to how to compare cancer insurance companies walks through the details.

3

Shortlist two or three companies. Favor A-range ratings and plans that fit your budget. See our 5 best cancer insurance policies for picks.

4

Get quotes side by side. A licensed agent who works with several companies can line up benefits and prices for you.

Want more background before you shop? Start at our cancer insurance home page.

Bottom Line

Supplemental cancer insurance companies differ most in how they sell, how their plans pay and how strong they are financially. Compare the outline of coverage, the in situ and recurrence rules, and the AM Best rating of the insurer on the policy, then get side-by-side quotes. Every one of these plans works beside your health insurance, not in place of it.

Get Free Cancer Insurance Quotes

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

Supplemental Cancer Insurance Companies — Frequently Asked Questions

➤ Which companies sell supplemental cancer insurance?

Well-known companies include Aflac, Colonial Life, Mutual of Omaha, Physicians Mutual, Washington National and ManhattanLife. Many large employers also offer cancer coverage through group benefits carriers.

➤ Which supplemental cancer insurance company is best?

No single company is best for everyone. The right one depends on whether you buy at work or on your own, how you want benefits to pay, your budget and the company’s financial strength.

➤ What AM Best rating should I look for?

Ratings in the A range, such as A (Excellent) or A+ (Superior), show strong ability to pay claims. B++ (Good) is solid but lower.

➤ Is Aflac the only supplemental cancer insurance company?

No. Aflac is well known, but many other companies sell cancer coverage, both at work and to individuals.

➤ Can I buy supplemental cancer insurance outside of work?

Yes. Companies such as Mutual of Omaha and Physicians Mutual sell individual cancer plans, and agents can quote several companies at once.

➤ Do supplemental cancer insurance companies cover pre-existing cancer?

Usually not. Most exclude cancer diagnosed before the policy starts or during the waiting period.

➤ Can I have policies from two companies?

Often yes, because many plans pay regardless of other coverage. Some policies limit overlapping coverage, so ask before you buy.

➤ Does supplemental cancer insurance replace health insurance?

No. It is limited-benefit coverage that pays cash to you. You still need health insurance, Medicare or Medicaid.

Cancer Insurance Quotes

Call a Licensed Agent Now

Compare cancer insurance plans and cash benefits from several insurance companies in one call.

☎ 1-888-891-0229

No obligation to buy

Ready to Compare? Get Free Cancer Insurance Quotes

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

ZRN Health & Financial Services, LLC, a Texas limited liability company