Speak with a licensed insurance agent

1-888-891-0229

Allstate Critical Illness Insurance: Who Owns It Now and What It Pays

Updated October 2026

Key Takeaway

Allstate critical illness insurance is a workplace, limited-benefit plan issued by American Heritage Life Insurance Company that pays a cash lump sum for covered conditions such as invasive cancer, heart attack and stroke. The Standard bought that business on April 1, 2025, so new and existing certificates are now serviced under The Standard name.

2027 by the Numbers

April 1, 2025

The Standard closed its purchase of the Allstate Benefits business (The Standard)

A (Excellent)

AM Best rating for American Heritage Life after the sale (AM Best, May 2025)

25%

share paid for carcinoma in situ in the Allstate Benefits brochures we reviewed

If you signed up for critical illness coverage at work under the Allstate Benefits name, your plan has not gone away, but the company behind it has changed hands. Allstate sold its employer voluntary benefits business, built around American Heritage Life Insurance Company, to The Standard.

This page explains what those certificates pay, how two different Allstate plan designs compare, what the ownership change means for people who already have coverage, and whether Allstate still sells anything you can buy on your own. For a general overview of the product type, read our critical illness insurance guide. Like every policy we cover, this is supplemental coverage that pays cash on top of your health plan. It does not replace health insurance.
Compare Critical Illness and Cancer Plans

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

Who Sells Allstate Critical Illness Insurance Today?

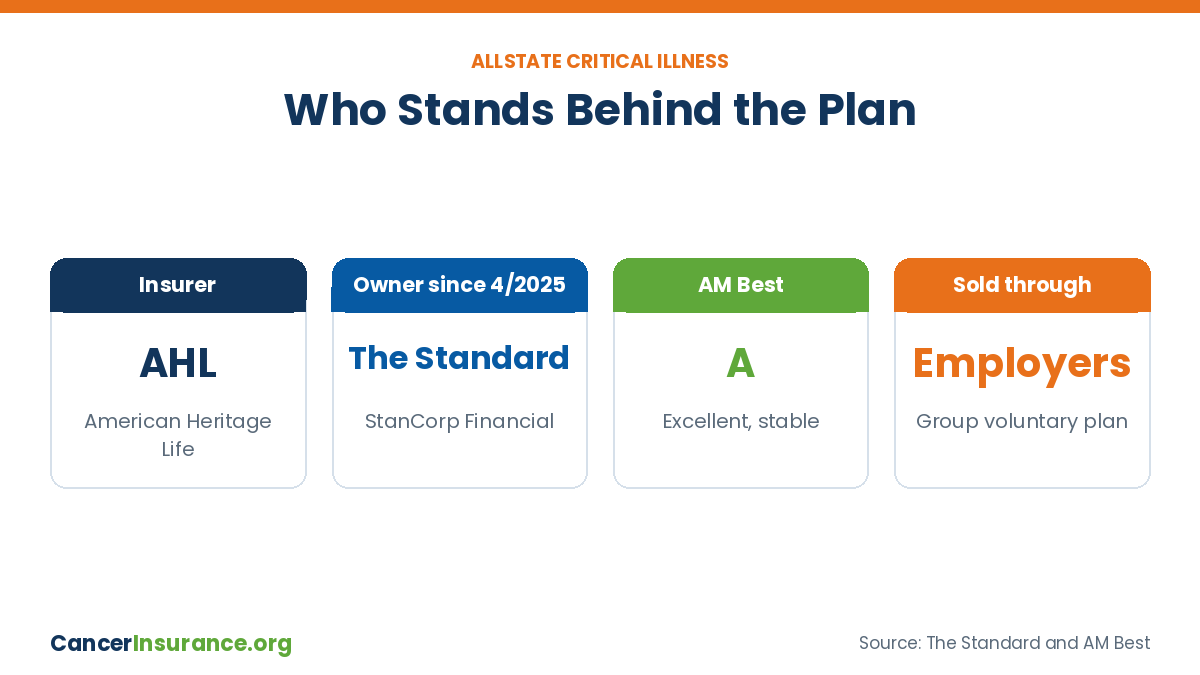
Allstate critical illness insurance at a glance: insurer, owner, AM Best rating and how it is sold

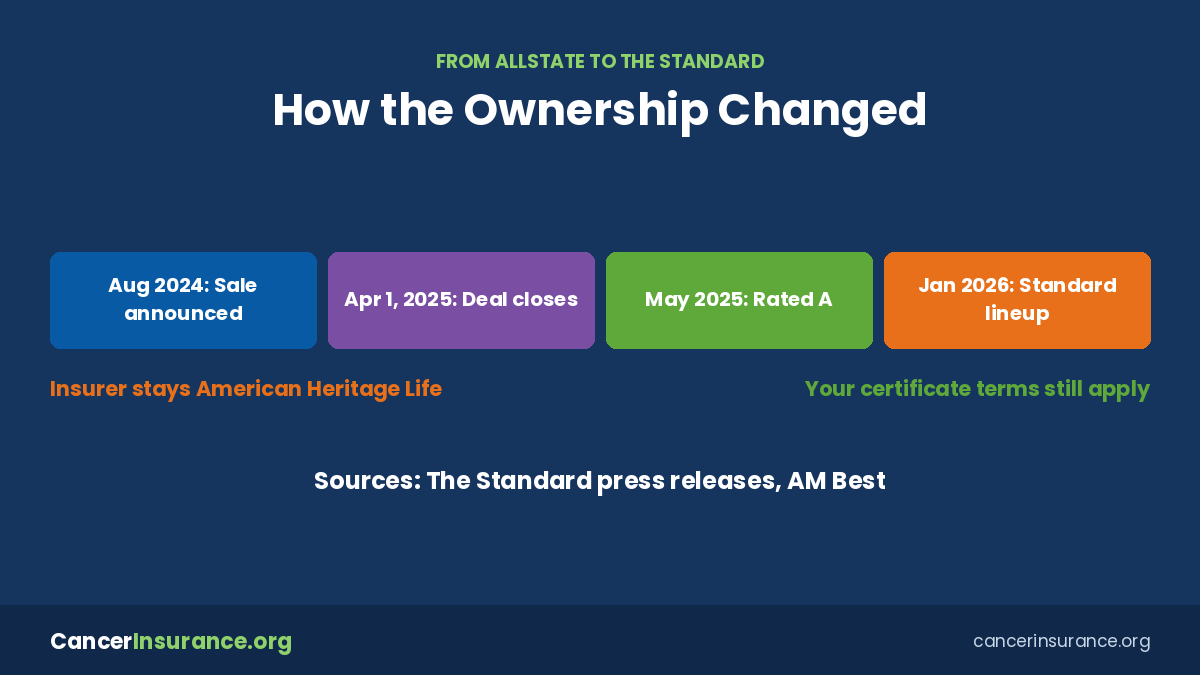
For years, the workplace plan was marketed as Allstate Benefits, the brand name for American Heritage Life Insurance Company in Jacksonville, Florida. In August 2024, The Standard (StanCorp Financial) agreed to buy Allstate’s employer voluntary benefits business, and the deal closed on April 1, 2025.

American Heritage Life is still the legal insurer on these certificates. What changed is the parent company. In October 2025, The Standard said the business now operates as American Heritage Employer Voluntary Benefits and that, starting January 1, 2026, it would fold the voluntary products, including critical illness, cancer, accident and hospital indemnity, into its own workplace lineup.

Keep in mind: Critical illness insurance is a limited-benefit, supplemental policy. It pays a set cash amount to you when a covered condition is diagnosed. It does not pay doctors or hospitals and is not a substitute for employer, ACA Marketplace or Medicare coverage.

Cancer Insurance Quotes

Call a Licensed Agent Now

Compare cancer insurance plans and cash benefits from several insurance companies in one call.

☎ 1-888-891-0229

No obligation to buy

Conditions the Allstate Benefits Plans Cover

Your employer chooses the plan design, so the list on your certificate may differ. In the Allstate Benefits brochures we read, each condition paid a fixed share of a basic benefit amount, most often $10,000 or $20,000 for the employee.

Heart conditions. Heart attack and stroke paid 100%. Coronary artery bypass surgery paid 25%. Some designs also listed heart transplant at 100%.

Organ and nerve conditions. Major organ transplant, end-stage renal failure and paralysis paid 100%. Alzheimer’s disease paid 25% in the plans we reviewed.

Cancer. Invasive cancer, including leukemia and lymphoma, paid 100%. Carcinoma in situ, an early cancer that has not spread, paid 25%.

Extra conditions in newer designs. One later form also listed benign brain tumor, coma of more than 14 days, complete blindness and complete loss of hearing at 100%, and advanced Parkinson’s disease at 25%.

Most designs also pay a small yearly health screening benefit when you get one covered test, such as a mammogram or colonoscopy. Cancer diagnosed before your coverage starts is not covered.

Two Allstate Plan Designs, Side by Side

Allstate Benefits sold more than one group form. No single brochure shows them together, so we lined up the employer documents we reviewed.

FeatureCategory design (form GVCIP1)Single-list design (form GVCIP2)
Employee benefit amounts seen$10,000 or $20,000$10,000 or $20,000
How conditions are grouped3 categories, each capped at 100%One list of 14 conditions
Invasive cancer / carcinoma in situ100% / 25%100% / 25%
Repeat diagnosisRecurrence pays 25% of a prior heart or organ benefit after 18 months with no treatmentOptional second event benefit pays the full amount again after more than 12 months; for cancer, no treatment in that time
Health screening$50 to $100 a year$100 a year
Waiver of premiumNot listed in the brochures we readEmployee premiums waived after 90 days of critical illness disability, up to 2 years
Spouse and children50% of employee amount50% of employee amount

Our comparison of Allstate Benefits brochures and flyers posted by employers (Pasco County Schools, Diocese of St. Petersburg, Missouri State University, County of San Diego). Older materials; your employer’s certificate and state rules control.

The big takeaway is the repeat-diagnosis rule. Under the category design, the recurrence benefit applied to the heart and organ categories, so a cancer that returned did not pay again under that rule. Where a second event cancer benefit was added, a new diagnosis more than 12 months after the first could pay the full amount again. If cancer is your main worry, ask which version your employer offers, or compare it with the cancer-only policies on our cancer insurance plans page.

What the Sale to The Standard Means for Current Members

Timeline of Allstate critical illness insurance moving from Allstate Benefits to The Standard

A change of owner does not rewrite a group certificate. Your benefits, exclusions and premiums are set by your employer’s group policy, and the insurer of record is still American Heritage Life. One employer that moved members over told staff in December 2025 that no forms had changed and that its Allstate cancer plan benefits stayed the same going into 2026.

1

Find your certificate. Look for American Heritage Life and the policy form number. That document, not the brand on the website, decides what you are paid.

2

Expect new names. Emails, ID cards, claim forms and websites are moving from Allstate Benefits to The Standard. Treat both as the same coverage.

3

Check at renewal. Your employer can change carriers or plan designs at a future open enrollment, as with any group plan. Read the new summary before you re-enroll.

4

Know the rating. AM Best lowered American Heritage Life from A+ to A (Excellent) in May 2025 after the sale, while saying its creditworthiness had not changed.

Broker tip: If you file a claim during the changeover, send it to the address or portal on your most recent plan materials and keep a copy of the pathology report and diagnosis date.

Compare Critical Illness and Cancer Plans

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

Enrollment, Pre-Existing Limits and Leaving Your Job

These plans are sold through employers to workers age 18 and older who are actively at work. At initial enrollment, the brochures we read described guaranteed issue up to a set amount, which means no health questions. Higher amounts or late sign-ups can require answers about your health.

Pre-existing rule. No benefit for a condition diagnosed in the first 12 months if you had symptoms, advice or treatment for it in the 12 months before coverage began. Some states shorten this to 6 months.

Diagnosis spacing. One form required at least 90 days between diagnosis dates for different illnesses.

Portability. When work coverage ends, you may keep it by sending a written request and the first premium, within 30 days in one brochure. It is not offered if coverage ended for unpaid premiums.

Dependent children generally stay covered until age 26. Spouse coverage ends at divorce or the employee’s death. For a broader view of whether workplace coverage is worth the payroll deduction, see is voluntary critical illness insurance worth it.

Can You Buy Allstate Critical Illness Coverage on Your Own?

Allstate kept a separate individual health arm, Allstate Health Solutions, after the workplace sale. Its 2025 materials describe a Term Life Critical Illness policy underwritten by National Health Insurance Company, Integon National Insurance Company or Integon Indemnity Corporation, depending on the state. Allstate has said that business may be kept or combined with another company, so availability can change.

How it pays. A lump sum on first diagnosis or treatment of a covered condition. Any critical illness payment reduces the life benefit too.

Who can apply. Named insured and spouse ages 18 to 60, with critical illness benefits payable up to age 85.

Benefit range. $25,000 to $150,000, with no medical exam required. One exclusion listed is a type of heart attack called NSTEMI.

Allstate’s individual cancer policy is covered on our Allstate cancer insurance page. To weigh other carriers, start with our list of cancer insurance providers.

Bottom Line

Allstate critical illness insurance is a workplace plan from American Heritage Life that now belongs to The Standard, and existing certificates keep their terms. It pays a lump sum for invasive cancer, heart attack, stroke and other listed conditions, but early cancer often pays only 25% and repeat-diagnosis rules vary by form. Read your certificate, and pair any critical illness plan with real health insurance.

Get Free Critical Illness Quotes

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

Allstate Critical Illness Insurance — Frequently Asked Questions

➤ Is Allstate Benefits now The Standard?

Yes. The Standard completed its purchase of Allstate’s employer voluntary benefits business on April 1, 2025. The plans are still issued by American Heritage Life Insurance Company, and the Allstate Benefits name is being replaced by The Standard over time.

➤ Will my Allstate critical illness benefits change because of the sale?

Not by itself. Your benefits come from your employer’s group policy and certificate. Changes can only happen through normal channels, such as your employer picking a new plan design at open enrollment.

➤ How much does Allstate critical illness insurance pay for cancer?

In the brochures we reviewed, invasive cancer paid 100% of the basic benefit and carcinoma in situ paid 25%. With a $20,000 basic benefit, that would be $20,000 or $5,000. Your certificate sets the actual amounts.

➤ Does Allstate critical illness pay again if cancer comes back?

It depends on the form. The category design’s recurrence benefit applied to heart and organ conditions. Plans with the second event cancer benefit could pay the full amount again for a new diagnosis more than 12 months later with no treatment in between.

➤ What is the health screening benefit on Allstate critical illness?

It is a small yearly payment, $50 or $100 in the plans we saw, for completing one covered test such as a mammogram, colonoscopy or EKG. It pays regardless of the result.

➤ What is American Heritage Life’s AM Best rating?

AM Best rates American Heritage Life Insurance Company A (Excellent) with a stable outlook. It lowered the rating from A+ in May 2025 after the sale to The Standard and said the change did not reflect weaker creditworthiness.

➤ Can I keep Allstate critical illness coverage after I leave my job?

Often, yes. The certificates include a portability provision that lets you continue coverage by applying in writing and paying the first premium within a short window, 30 days in one brochure.

➤ Does Allstate critical illness insurance replace health insurance?

No. It is a supplemental, limited-benefit policy that pays cash to you. You still need major medical coverage through work, the ACA Marketplace or Medicare.

Cancer Insurance Quotes

Call a Licensed Agent Now

Compare cancer insurance plans and cash benefits from several insurance companies in one call.

☎ 1-888-891-0229

No obligation to buy

Ready to Compare? Get Free Cancer Insurance Quotes

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

ZRN Health & Financial Services, LLC, a Texas limited liability company