Updated November 2026
Key Takeaway
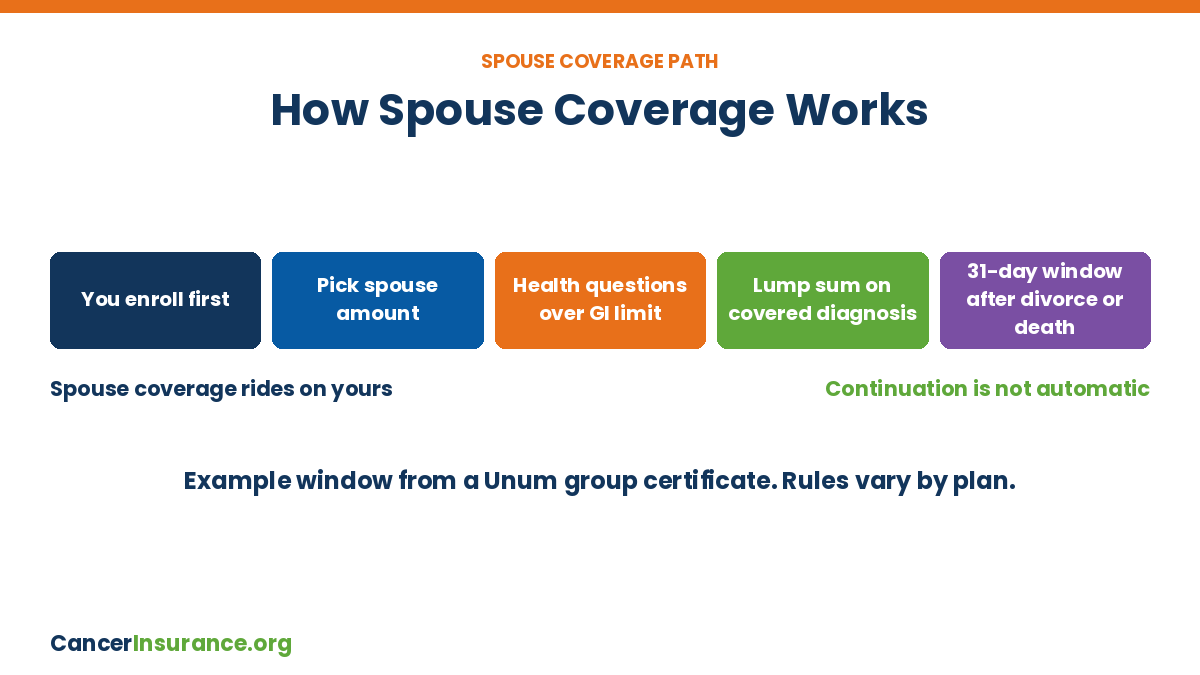
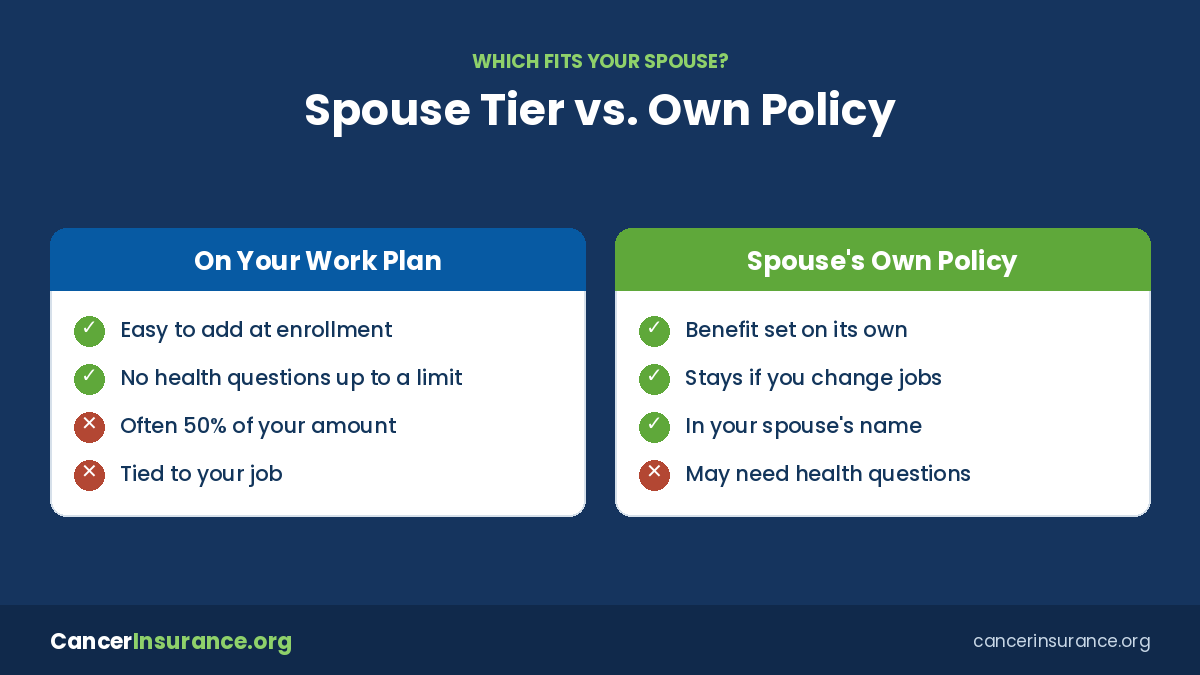
Spouse critical illness insurance is coverage you add for your husband, wife or domestic partner through your own workplace critical illness plan, and it usually pays your spouse a lump sum set at 50% to 100% of your benefit or a fixed amount such as $5,000 to $15,000. In most group plans you must enroll yourself first, and amounts above the guaranteed issue limit require health questions.
2027 by the Numbers
50%
spouse share of the employee benefit in MetLife, Guardian and Unum plan summaries reviewed
$30,000
spouse guaranteed issue cap in one 2026 Cigna plan summary
31 days
window for a spouse to continue Unum coverage after the employee’s death or a divorce
Open enrollment screens often show an Employee + Spouse option next to the critical illness plan. Checking it gives your partner a lump-sum benefit for a covered diagnosis such as cancer, heart attack or stroke. Spouse coverage follows its own rules, though: a smaller benefit, different age limits and, in some plans, a different way of setting the price.
This guide lays out those rules using the carriers’ own published plan summaries and certificates. If you are new to the product, start with our overview of critical illness insurance. Like any critical illness policy, spouse coverage is supplemental, limited-benefit insurance. It pays cash on top of a health plan and does not replace employer, ACA Marketplace or Medicare coverage.