Speak with a licensed insurance agent

1-888-891-0229

Can I Get Cancer Insurance After Diagnosis? Rules, Timing and Options

Updated October 2026

Key Takeaway

Usually not right away. No cancer policy pays for a cancer you already have, and most individual plans decline you while you are in treatment or recently treated. Your options open up again once you pass the insurer’s cancer-free lookback period, which is often 5 years.

Cancer insurance works best when you buy it before you need it. That is frustrating to hear after a diagnosis, but it is not the end of the story. What you can get depends on where you are today: in treatment, recently finished, or cancer-free for several years.

This guide explains the health questions insurers ask, how lookback and pre-existing condition rules work, and what you can do now. Keep in mind that cancer insurance is a supplemental, limited-benefit policy that pays cash on top of your health plan. It does not replace health insurance, and your health plan still covers your treatment.
Compare Cancer Insurance Plans

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

Can I Get Cancer Insurance After a Cancer Diagnosis?

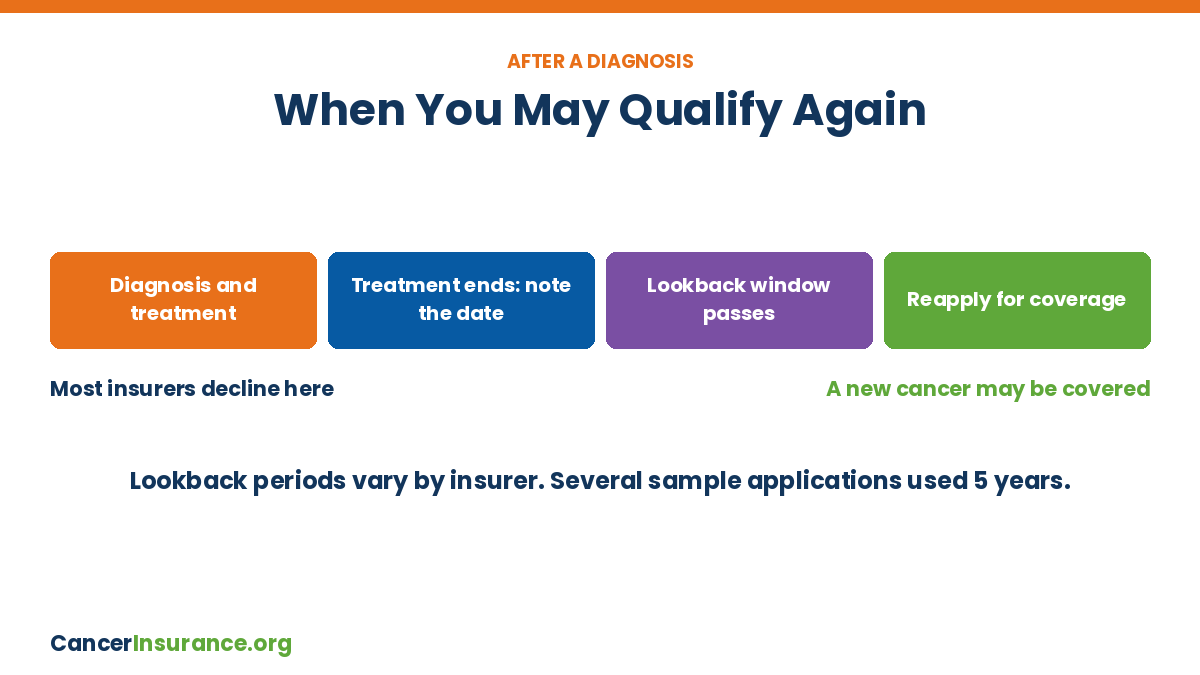
Timeline showing when you can get cancer insurance after diagnosis, from treatment to reapplying after the lookback

The honest answer is “not yet” for most people in active treatment, and “maybe” for people who finished treatment years ago. Individual cancer policies are medically underwritten. That means the application asks about your health, and a recent cancer is the most common reason an application is turned down.

In treatment now. Expect most individual cancer policies to decline you. Put your energy into using the coverage you already have.

Recently treated. If your last diagnosis or treatment falls inside the insurer’s lookback window, you will likely be declined until that window passes.

Cancer-free for years. Once you are outside the lookback window, many insurers may accept you. A new, unrelated cancer could then be covered.

Be honest: Leaving a past cancer off the application can lead to a denied claim or a cancelled policy later. Answer every health question exactly as asked.

Cancer Insurance Quotes

Call a Licensed Agent Now

Compare cancer insurance plans and cash benefits from several insurance companies in one call.

☎ 1-888-891-0229

No obligation to buy

What Cancer Insurance Applications Ask

Every insurer writes its own questions, but they follow a pattern. We reviewed sample cancer applications from large carriers. Several asked whether you had ever been diagnosed with or treated for cancer, then whether that diagnosis or treatment happened within the last five years.

Question typeWhat it looks forWhy it matters
Ever had cancer?Any past cancer diagnosis or treatmentOpens follow-up questions about timing and type
Within the last 5 years?Diagnosis or treatment inside the lookback windowA yes here is a common reason for a decline
Certain cancer typesSome forms ask about leukemia, lymphoma or cancer that spread to lymph nodesThese can be asked about with no time limit
Skin cancerBasal cell or other skin cancersOften handled separately, and some forms exclude basal cell from the question
Pending testsBiopsies or tests you are waiting onUnresolved results can delay or stop an approval

Based on sample cancer applications from large carriers. Questions and lookback periods differ by insurer, plan and state.

Because questions vary, one insurer may decline you while another accepts you. That is a big reason to compare several cancer insurance plans if you have a history.

Pre-Existing Condition Rules vs. Waiting Periods

Two separate rules decide what a policy will pay. People often mix them up, and that leads to surprise denials.

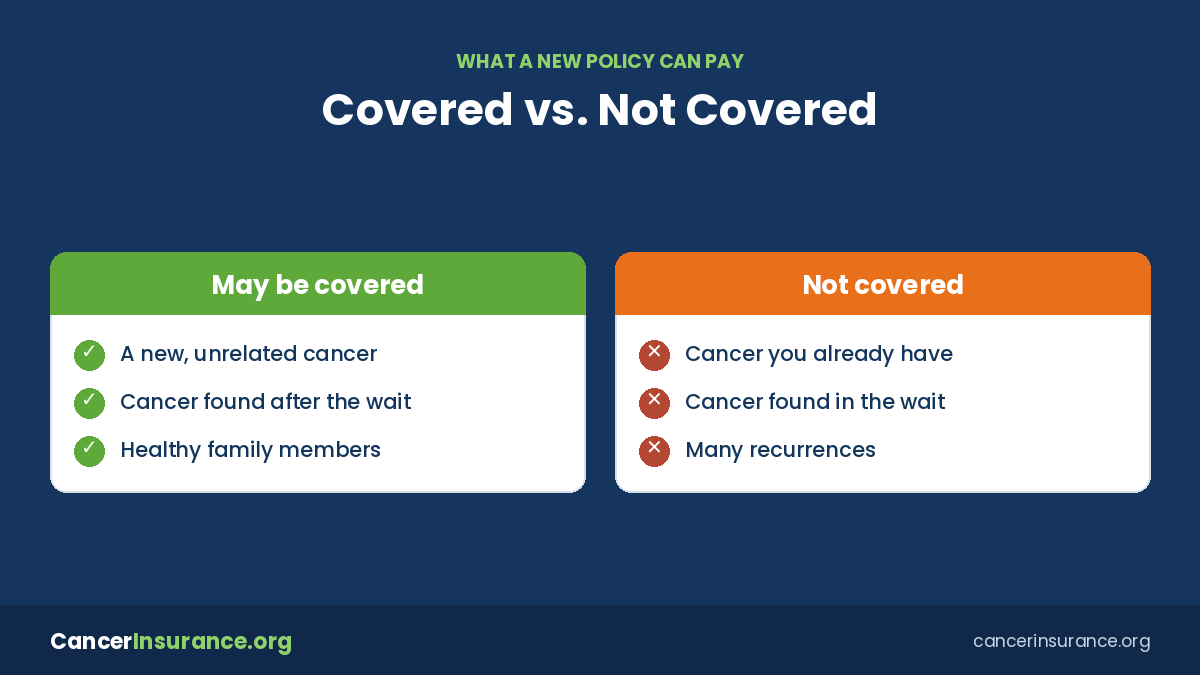
Pre-existing condition rule. A cancer diagnosed, tested or treated before coverage starts, or during a set lookback, is not covered. Some group plans also exclude a recurrence of an earlier cancer.

Waiting period. Applies to everyone, healthy or not. Many cancer policies use 30 days, and some carriers use longer periods for people 65 and older. A cancer found during this time is generally not covered.

Getting past the waiting period never turns an existing cancer into a covered one. A cancer you had before the policy started stays excluded. Learn more in our guide to cancer insurance waiting periods.

Good to know: One sample policy we reviewed lets you cancel for a full premium refund if cancer is diagnosed before the policy has been in force 30 days. Ask whether your policy has the same option.

Options If You Have Already Been Diagnosed

What cancer insurance after diagnosis covers compared with what stays excluded

An individual cancer policy may be off the table for now, but these paths are still worth checking.

1

Lean on your health insurance. ACA Marketplace and employer health plans cannot turn you down or charge you more because of cancer, and Medicare covers cancer treatment. Make sure your main plan is solid first.

2

Check workplace plans. Cancer and critical illness plans at work are often offered with few or no health questions during enrollment. Expect a pre-existing condition limit, so read the plan rules.

3

Write down your cancer-free date. Note the date your last treatment ended. Once you pass an insurer’s lookback window, apply again.

4

Ask about financial help. Hospital social workers and cancer nonprofits can help with travel, lodging and other costs during treatment.

To see how insurers look at a past cancer in more detail, our page on cancer insurance and pre-existing conditions goes deeper on how insurers treat a history.

Compare Cancer Insurance Plans

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

Workplace Plans After a Diagnosis

Group cancer plans sold through an employer are often the easiest way in. Many are offered on a guaranteed issue basis during open enrollment, which means no medical questions for the base amount. The catch is the pre-existing condition clause.

FeatureTypical group planTypical individual plan
Health questionsOften few or none at enrollmentYes, with a lookback period
Pre-existing cancerExcluded for a set time, or excluded for that cancerExcluded
New, unrelated cancerMay be covered after limits are metMay be covered once approved
Late enrollmentMay require health questionsHealth questions any time

Rules vary by employer, plan and insurer. Read the plan certificate before you enroll.

One group plan example we reviewed used a three-month lookback and a 12-month exclusion period. Even then, the original cancer stayed excluded, while a different, unrelated cancer could be covered. See our guide to group cancer insurance for more.

Protect Your Family and Plan Ahead

Your diagnosis does not stop a healthy spouse or adult child from buying their own policy. They qualify on their own health answers, and buying while healthy gives them the most choices.

Healthy spouse. Can usually apply now on their own application.

Adult children. Can apply now. Buying younger often means a lower starting premium.

You. Reapply once you pass the insurer’s lookback window.

When the time comes to shop, compare carriers in our 5 best cancer insurance policies guide. A licensed agent can also tell you which insurers are most likely to accept your history before you apply.

Bottom Line

Cancer insurance will not pay for a cancer you already have, and most individual policies decline you during treatment or inside the lookback window. Check workplace plans now, track your cancer-free date so you know when to reapply, and help healthy family members get covered while they qualify.

Get Free Cancer Insurance Quotes

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

Cancer Insurance After Diagnosis — Frequently Asked Questions

➤ Can I get cancer insurance after a cancer diagnosis?

It is hard while you are in treatment or recently treated. Most individual cancer policies ask about past cancer and decline applicants inside their lookback window. Many insurers may accept you once you have been cancer-free for the period they require.

➤ How long do I have to be cancer-free to get cancer insurance?

It depends on the insurer. Several sample applications we reviewed asked about cancer within the last five years, while some asked about certain cancers, like leukemia or lymphoma, with no time limit. Ask each insurer how its questions apply to you.

➤ Will cancer insurance cover a recurrence of my old cancer?

Usually not if the cancer was present or treated before your policy started. Some plans specifically exclude a recurrence of a previously diagnosed cancer. A new, unrelated cancer may be covered once you are approved and past the waiting period.

➤ What is the difference between a waiting period and a pre-existing condition rule?

A waiting period is a short time after coverage starts, often 30 days, when a new diagnosis is not covered. A pre-existing condition rule excludes a cancer you had before coverage began. Waiting out the waiting period does not cover an existing cancer.

➤ Can I get cancer insurance through work after a diagnosis?

Often yes. Employer cancer plans are frequently offered with few or no health questions during enrollment. Most still limit or exclude benefits for a pre-existing cancer, so read the plan’s rules before you count on it.

➤ Does my health insurance still cover cancer treatment?

Yes. ACA Marketplace and employer health plans cannot deny you or charge more because of cancer, and Medicare covers cancer treatment. Cancer insurance only adds cash on top of your health plan.

➤ Can my family get cancer insurance if I have cancer?

Usually yes. A healthy spouse or adult child applies on their own health answers, so your diagnosis does not stop them from getting their own policy.

➤ What happens if I leave cancer off my application?

The insurer can deny a claim or cancel the policy if it finds a history you did not report. Always answer the health questions honestly, and ask a licensed agent which insurers fit your history.

Cancer Insurance Quotes

Call a Licensed Agent Now

Compare cancer insurance plans and cash benefits from several insurance companies in one call.

☎ 1-888-891-0229

No obligation to buy

Ready to Compare? Get Free Cancer Insurance Quotes

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

ZRN Health & Financial Services, LLC, a Texas limited liability company