Speak with a licensed insurance agent

1-888-891-0229

Compare Manhattan Life Cancer Insurance Plans Side by Side

Updated October 2026

Key Takeaway

To compare Manhattan Life cancer insurance plans, start with how each one pays: Cancer Care Plus pays set amounts as you go through treatment, while the Cancer and/or Heart Attack and Stroke plan pays one lump sum at diagnosis. Critical Protection and Recovery is mainly a heart and critical illness plan with cancer as an add-on.

ManhattanLife changed its cancer lineup in 2026. Its stand-alone Cancer First Occurrence Benefit product stopped being sold on February 1, 2026, which leaves three plans for new buyers who want cancer protection. Each one is built for a different kind of worry.

Below we put the plans side by side, show the benefit ranges from ManhattanLife brochures, and walk through which plan fits which situation. For background on the company itself, see our Manhattan Life cancer insurance overview. Every plan here is supplemental, limited-benefit coverage. It pays cash on top of your health plan and does not replace health insurance.
Compare Cancer Insurance Plans

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

Manhattan Life Cancer Plans at a Glance

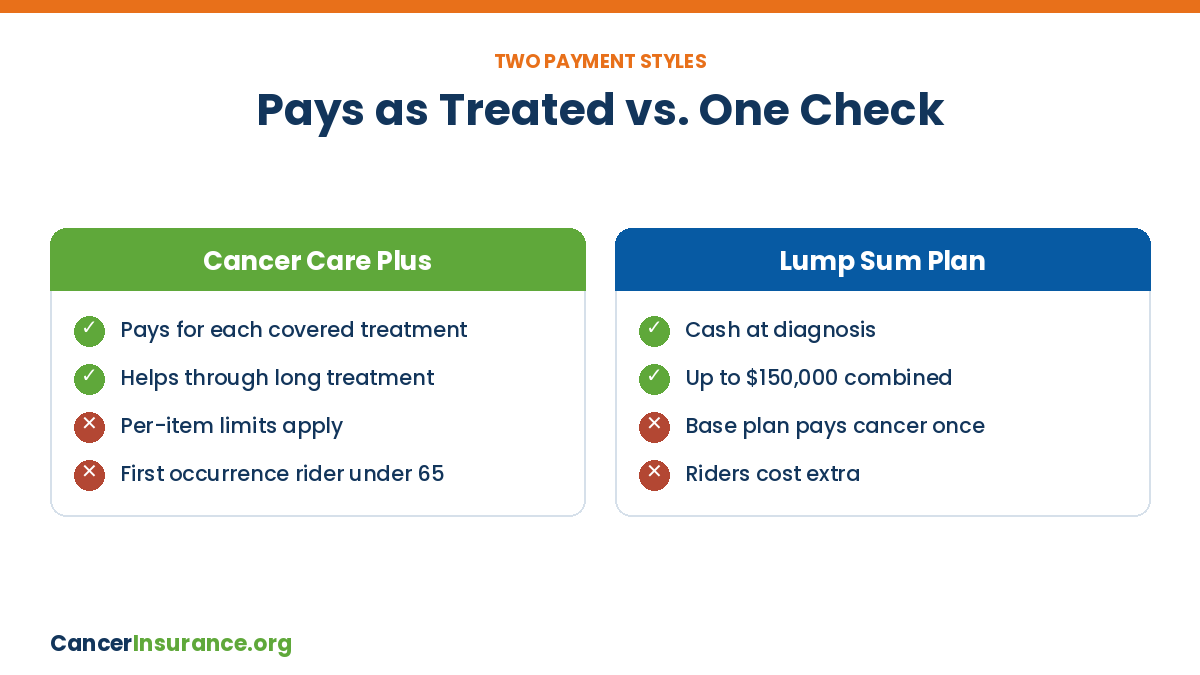
Compare Manhattan Life cancer insurance plans: treatment-based Cancer Care Plus versus the lump sum plan

The quickest way to compare Manhattan Life cancer insurance plans is by what triggers a payment and how often it pays.

FeatureCancer Care PlusLump Sum Cancer and/or Heart & StrokeCritical Protection and Recovery
Main purposeCancer treatment costsOne check at diagnosisHeart attack, stroke and other critical illness
Cancer coverageBuilt inChoose cancer, heart, or bothOptional add-on
Payment styleScheduled benefits per treatment or daySingle lump sumFirst occurrence, hospital and monthly income
Highest stated benefitVaries by itemUp to $150,000 combinedNot listed online
Other diseasesMS, muscular dystrophy, epilepsy, meningitisHeart attack and stroke if chosenComa, burns, organ transplant, paralysis and more
Key ridersICU, Critical CareCancer Recurrence, Heart & Stroke RestorationCancer benefit

Based on ManhattanLife product pages and brochures. Benefits, riders and availability vary by state; your policy controls.

Cancer Insurance Quotes

Call a Licensed Agent Now

Compare cancer insurance plans and cash benefits from several insurance companies in one call.

☎ 1-888-891-0229

No obligation to buy

Cancer Care Plus: Benefits and Limits

Cancer Care Plus works like a menu of set payments. Each time you have a covered treatment, hospital day or surgery, the plan pays up to the amount listed for your plan level. A ManhattanLife brochure lists issue ages 18 to 69 and says the plans are guaranteed renewable.

BenefitRange shown in brochure
Radiation, chemotherapy, immunotherapyActual charges up to $2,500 to $7,500 per month
SurgeryUp to $2,500 to $4,000 per surgery
Daily hospital confinement$100 to $300 per day, first 70 days of each stay
Cancer screening test$50 or $100 once per calendar year
First Occurrence rider$1,000 to $10,000 once; not sold at 65 or older
ICU rider$600 per day in ICU, up to 30 days per stay

Ranges come from one ManhattanLife Cancer Care Plus brochure and are not a quote. ICU rider benefits drop by half at age 70.

Watch for: The first occurrence benefit does not pay for skin cancer, outpatient surgery done in a doctor’s office is not paid, and screening benefits don’t pay for free testing programs. Read the outline of coverage for your state before you buy.

Lump Sum Cancer and/or Heart Attack & Stroke Plan

This plan is the simplest of the three. You choose cancer coverage, heart attack and stroke coverage, or both. When a covered diagnosis is confirmed, the plan pays one cash amount you can use however you want. ManhattanLife says combined lump sum benefits can reach $150,000, and a brochure shows each part offered from $5,000 to $75,000.

Rates by age. The brochure we reviewed shows base rates for ages 20 to 84, so it can fit working adults and Medicare-age buyers.

Heart waiting period. The heart attack and stroke part has a 30-day waiting period, and a pre-existing heart condition isn’t covered until you’ve been insured for 12 months.

Recurrence rider. If cancer comes back after a treatment-free period, this rider pays part of the original benefit again.

Restoration rider. Without it, heart and stroke coverage ends after the first lump sum payment.

If one large check is what you want, also compare other lump sum cancer insurance options before you choose.

How the Cancer Recurrence Rider Pays

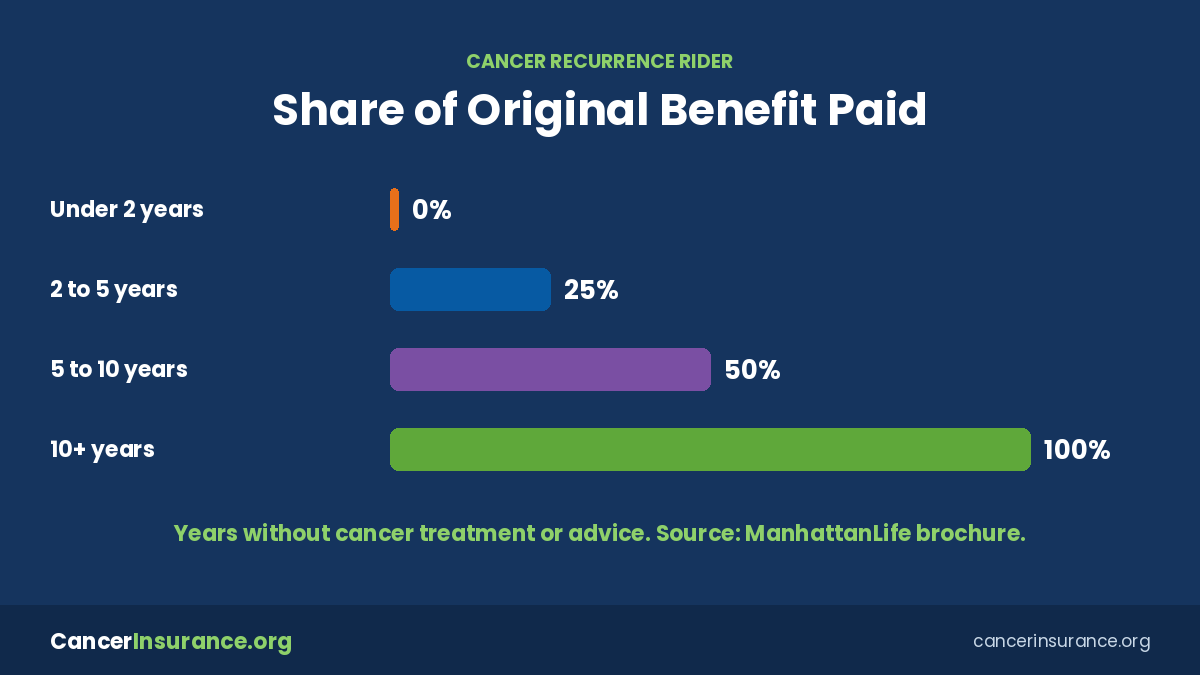
Manhattan Life cancer recurrence rider payout percentage by treatment-free years when you compare plans

Cancer coming back is a real risk, and a one-time lump sum does not help with a second diagnosis. The recurrence rider on the lump sum plan pays a percentage of your original cancer benefit based on how long you went without treatment or medical advice for cancer.

The clock matters. The payout grows the longer you go without cancer treatment or medical advice for cancer. Under two years, it pays nothing.

A worked example. A ManhattanLife brochure example shows a recurrence after six treatment-free years paying 50% of the original cancer benefit.

Only on the lump sum plan. The recurrence rider is offered with the Cancer and/or Heart Attack and Stroke policy, not as part of Cancer Care Plus.

Broker tip: In the brochure we reviewed, the recurrence and restoration riders were priced only for ages 20 to 54. If you are older, ask whether the riders are available to you before you count on them.

Compare Cancer Insurance Plans

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

Critical Protection and Recovery With Cancer

Critical Protection and Recovery is ManhattanLife’s broad critical illness plan. It covers heart attack, stroke, coma, major third-degree burns, major organ transplant, coronary bypass surgery, paralysis and end-stage kidney failure. Cancer is an optional benefit you can add.

Several payment types. Its listed benefits include a first occurrence benefit, a monthly income benefit, a recurrence benefit, hospital confinement, ambulance, lodging and transportation.

Waiver of premium. The plan lists a waiver of premium benefit, which generally means premiums can stop during a qualifying claim. Check the policy for the exact terms.

Best fit. People whose family history leans toward heart disease, who also want some cancer protection in the same policy.

To learn how cancer and critical illness coverage differ in general, read cancer insurance vs. critical illness.

Which Manhattan Life Plan Should You Choose?

The right plan depends on what you want the money to do. Here is a simple way to decide.

1

Want help through long treatment? Cancer Care Plus pays again and again as chemotherapy, radiation and hospital days add up.

2

Want one fast check? The lump sum plan pays once at diagnosis, which helps with deductibles and lost income right away.

3

Worried about heart attack or stroke too? Add heart and stroke to the lump sum plan, or look at Critical Protection and Recovery with the cancer option.

4

Check the cost. See typical premium factors on our Manhattan Life cancer insurance cost page, then compare with other cancer insurance plans.

ManhattanLife’s group companies were rated B++ (Good) by AM Best after a January 2022 upgrade. A licensed agent can quote ManhattanLife next to higher-rated companies so you can weigh price, benefits and strength together.

Bottom Line

When you compare Manhattan Life cancer insurance plans, the choice comes down to payment style. Cancer Care Plus pays as treatment happens, the lump sum plan pays one check at diagnosis, and Critical Protection and Recovery adds cancer to a heart and critical illness plan. All three are supplemental and work beside your health insurance.

Get Free Cancer Insurance Quotes

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

Compare Manhattan Life Cancer Insurance Plans — Frequently Asked Questions

➤ Which Manhattan Life cancer plans can I buy in 2026?

New buyers can look at Cancer Care Plus, the lump sum Cancer and/or Heart Attack and Stroke plan, and Critical Protection and Recovery with an optional cancer benefit. The stand-alone Cancer First Occurrence product stopped being sold on February 1, 2026.

➤ Which Manhattan Life plan pays the most?

The lump sum plan has the highest stated amount, up to $150,000 when cancer and heart coverage are combined. Cancer Care Plus can add up over a long treatment, so the better choice depends on how you expect to use the money.

➤ What ages can buy Cancer Care Plus?

A ManhattanLife brochure lists issue ages 18 to 69 for Cancer Care Plus. Its First Occurrence rider is not available at age 65 or older.

➤ Does the lump sum plan pay more than once?

The base plan pays once for cancer. The optional Cancer Recurrence rider can pay 25%, 50% or 100% of the original benefit if cancer returns after two, five or ten treatment-free years.

➤ Does Cancer Care Plus cover diseases other than cancer?

Yes. It also covers specified diseases including multiple sclerosis, muscular dystrophy, epilepsy and meningitis, according to ManhattanLife.

➤ Is there a waiting period on Manhattan Life cancer plans?

Yes. Cancer diagnosed during the waiting period is not covered, and the heart attack and stroke part of the lump sum plan has a 30-day waiting period. Ask for the exact cancer waiting period in your state.

➤ Do Manhattan Life cancer plans replace health insurance?

No. They are supplemental, limited-benefit policies that pay set cash amounts to you. You still need health insurance, Medicare or another major medical plan.

➤ Can I have more than one Manhattan Life plan?

Some people pair a lump sum plan with a treatment-based plan, but carriers set their own limits on overlapping coverage. Ask your agent whether combining plans is allowed in your state.

Cancer Insurance Quotes

Call a Licensed Agent Now

Compare cancer insurance plans and cash benefits from several insurance companies in one call.

☎ 1-888-891-0229

No obligation to buy

Ready to Compare? Get Free Cancer Insurance Quotes

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

ZRN Health & Financial Services, LLC, a Texas limited liability company