Speak with a licensed insurance agent

1-888-891-0229

Hartford Critical Illness Insurance: Severity Tiers, Cancer Pay and the 500% Cap

Updated November 2026

Key Takeaway

Hartford critical illness insurance is a group plan offered through employers and issued by Hartford Life and Accident Insurance Company that pays you a cash lump sum, commonly $10,000, $20,000 or $30,000, after a covered diagnosis such as invasive cancer, heart attack or stroke. Many conditions pay on a severity scale, so a milder diagnosis pays a smaller share and the most serious form pays 100%.

2027 by the Numbers

A+ (Superior)

AM Best financial strength rating for Hartford Life and Accident Insurance Company, affirmed July 22, 2026 (AM Best)

160+

conditions in the critical illness product The Hartford launched in March 2022 (The Hartford)

500%

lifetime benefit maximum per covered person in the Roanoke College and Jefferson County, TX plan summaries (The Hartford)

The Hartford is better known for car and business insurance, but its employee benefits arm sells voluntary coverage at many workplaces. With its critical illness plan, the premium comes out of your paycheck and any benefit is paid in cash to you.

This guide covers who issues the certificate, how the severity scale works, how three published Hartford designs differ and when a second claim can pay. First, the key point: this is supplemental, limited-benefit insurance for specified diseases. It does not pay providers, is not major medical coverage and cannot replace health insurance from work, the ACA Marketplace or Medicare. For how lump-sum products work in general, read our critical illness insurance overview.
Compare Critical Illness and Cancer Options

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

Who Issues Hartford Critical Illness Coverage Now

Key facts on the company behind Hartford critical illness insurance in 2026

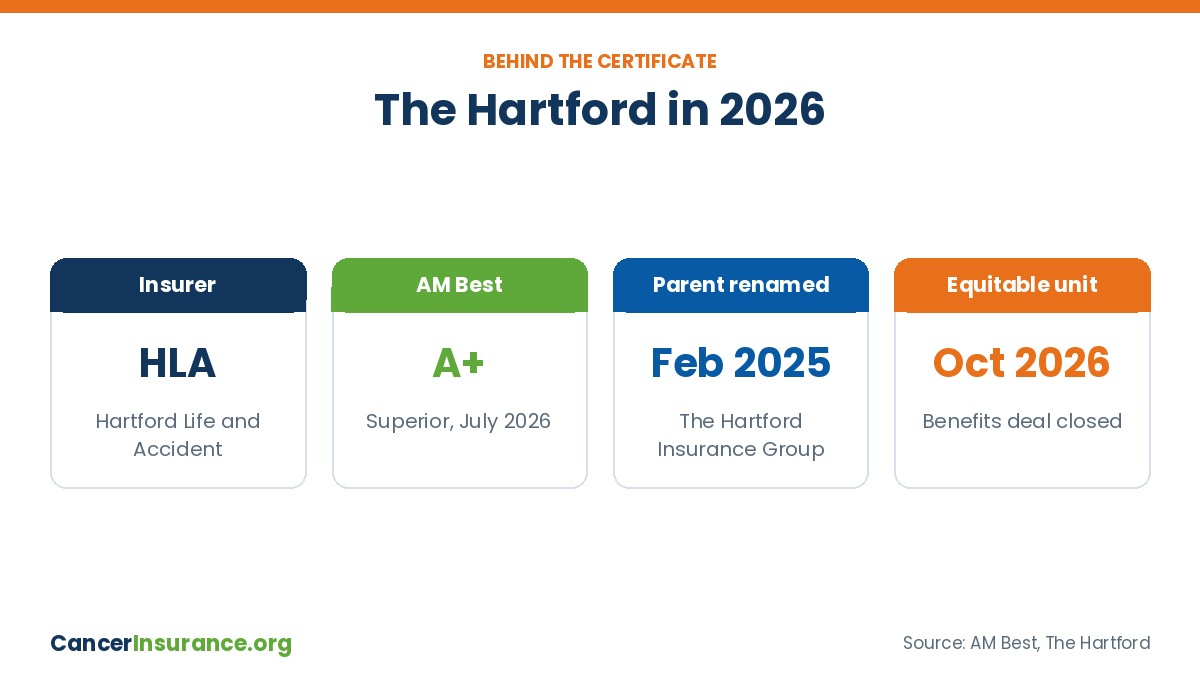
The legal insurer on a Hartford group certificate is Hartford Life and Accident Insurance Company, which uses The Hartford as its brand. The certificates are filed as forms GBD-3600 and GBD-3700, or a state version of them. AM Best affirmed that company’s A+ (Superior) financial strength rating with a stable outlook on July 22, 2026.

Two corporate changes explain any new names on your paperwork. On February 6, 2025, the parent company changed its name from The Hartford Financial Services Group, Inc. to The Hartford Insurance Group, Inc. Then, on August 4, 2026, The Hartford agreed to buy Equitable’s employee benefits business, about $500 million in premium that includes supplemental health. It announced in October 2026 that the deal had closed.

Paperwork check: If your supplemental health coverage came from Equitable, the plan terms, rates and claim steps in your current certificate still apply until your employer gets new documents. Ask the benefits office which insurer will be named at the next renewal.

Cancer Insurance Quotes

Call a Licensed Agent Now

Compare cancer insurance plans and cash benefits from several insurance companies in one call.

☎ 1-888-891-0229

No obligation to buy

Three Ways a Hartford Benefit Can Be Paid

The Hartford’s 2026 product sheet sorts every benefit into one of three payment types, which tells you whether to expect the full elected amount or only part of it.

Partial (P). Pays a fixed share below 100% of your coverage amount. Carcinoma in situ, advanced cancer, heart arrhythmia and pulmonary embolism are listed examples.

Severity-based (S). The share changes with how serious the illness is, whether the repair is major or minor, or whether the diagnosis is early or advanced. Stroke, coronary artery disease, dementia and type 2 diabetes work this way.

Fixed indemnity (I). Pays a set dollar amount instead of a percentage. Mammograms, second opinions, family care and ambulance benefits are examples.

At the March 2022 launch, The Hartford said employers could pick partial levels of 10%, 25% or 50%, and larger groups can now remove single illnesses. Cancer itself can be dropped where the employer also offers a stand-alone cancer policy, which is why some workers see a Hartford critical illness plan with no cancer line at all. If that is your case, our cancer insurance plans guide shows how a cancer-only policy pays.

Hartford Plan Summaries Compared Line by Line

The Hartford’s public pages do not show how employer choices differ, so we compared two employer plan summaries with The Hartford’s own small-group summary. All three name Hartford Life and Accident as the insurer.

Plan featureRoanoke College (2025)Jefferson County, TX (2026)Hartford small-group summary
Employee amounts$10,000, $20,000 or $30,000$10,000, $20,000 or $30,000$5,000 steps to $10,000 (4-24 lives) or $20,000 (25-99 lives)
Spouse / child100% / 50% of employee100% / 50% of employee100% / 50% of employee
Health questionsNot stated in summaryNone; all amounts guaranteed issueNone if at least 4 lives enroll
Carcinoma in situ25% first claim100% first claim25% first claim
Skin cancer$250 per year$250, and $250 again on reoccurrence$250 one time only
Wait before a repeat claim180 days180 days180 days
Yearly health screening$50 per person$75 per policy year$50, if the employer adds it
Lifetime maximum500% per person500% per personNot stated

Our comparison of The Hartford plan summaries posted by Roanoke College and Jefferson County, Texas, and The Hartford’s Critical Illness 3.0 small-group summary. Your own certificate and state rules control.

Invasive cancer paid 100% in all three, with a 100% reoccurrence benefit. The real spread is in early cancer: Jefferson County’s plan pays carcinoma in situ at the full amount, while the other two pay a quarter. Premiums are set group by group. Lansing Community College lists $10,000 of employee-only coverage at $2.55 a month under age 25 and $32.47 at ages 65 to 69.

Heart and Stroke Claims: Where the Severity Scale Bites

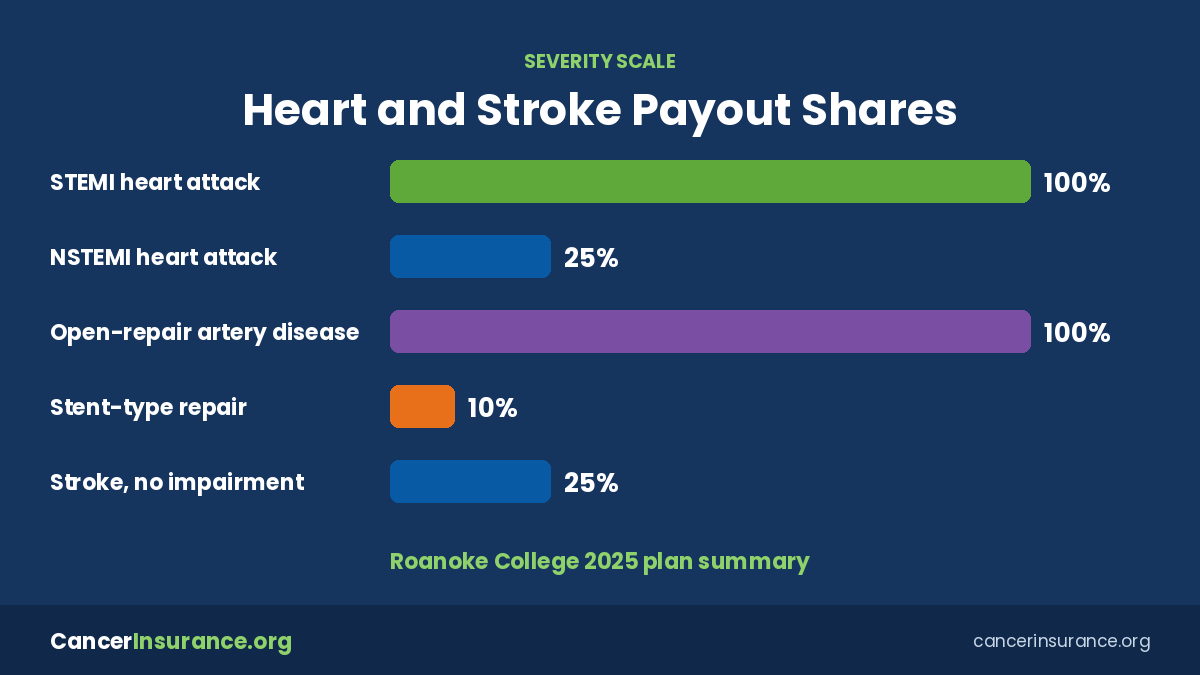
Hartford critical illness insurance heart and stroke payouts by severity in one employer plan

Heart and stroke benefits are split more finely than cancer. In Roanoke College’s 2025 summary, a STEMI heart attack, the type with a fully blocked artery, pays 100%, while an NSTEMI heart attack pays 25%. Coronary artery disease pays 100% for open surgery but only 10% for an endovascular repair such as a stent.

Stroke follows the same idea. Roanoke pays 25% for a stroke without lasting impairment, a group that includes a mini-stroke (TIA), and 100% for a mild, moderate or severe stroke. The Hartford small-group summary grades it more steeply: 10% for mild, 25% for moderate and 100% for severe.

Read the definition: The severity tier is set by the definitions in the certificate, such as the test results or the type of procedure required. Ask for the certificate, not just the one-page flyer, before counting on a 100% payout for a heart or stroke event.

Compare Critical Illness and Cancer Options

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

Second Claims, Separation Periods and the 500% Ceiling

A Hartford plan can pay more than once, within limits. This order follows the Roanoke and Jefferson County summaries.

1

First diagnosis pays. The initial benefit is paid at the share listed for that illness, such as 100% for invasive cancer.

2

A related illness must wait. A related critical illness diagnosed within 30 days of the first one does not pay its own initial benefit. The small-group summary applies a 30-day gap between initial claims.

3

The same illness can pay again. A reoccurrence benefit is payable once 180 days have passed after a benefit was paid for that illness. It is figured as a share of the first benefit.

4

Some illnesses pay once. End-stage renal disease, bone marrow failure, paralysis, loss of sight, hearing or speech, and advanced dementia, Parkinson’s, ALS and MS carry no reoccurrence benefit in the Roanoke design.

5

Payments stop at the cap. Critical illness benefits end when the policy benefit maximum, 500% of the coverage amount per person in both employer plans, is reached.

The 2026 product sheet shows employers another option: reoccurrence paid at 25% to 100% with a 12-month separation instead of 180 days. Your summary tells you which rule your group chose. Our critical illness lump sum payment page explains how that cash can be used.

Enrolling, Leaving Your Job and What the Plan Is Not

Getting in. You must be actively at work on the day coverage takes effect. Hartford designs can cover a spouse and children, with child eligibility up to age 26 in the 2026 product sheet.

Older workers. Employers can set an age when employee coverage ends, from 65 to 85 in the product sheet. Check the summary for an age limit before relying on the plan into retirement.

Leaving work. Summaries describe Continuation of Coverage and Extended Continuation options, both tied to paying premiums. The certificate sets the exact terms.

Past diagnoses. Jefferson County’s summary pays nothing for an illness diagnosed before your effective date, and some states require a pre-existing condition limit.

The plan is not major medical coverage and does not meet the ACA minimum essential coverage rule. In New York it is called Specified Disease coverage, and it is not sold in every state. If your employer does not offer The Hartford, compare individual carriers in our cancer insurance providers list or the 5 best cancer insurance policies.

Bottom Line

Hartford critical illness insurance is a workplace plan from Hartford Life and Accident, rated A+ by AM Best, that pays cash on a severity scale, with invasive cancer at 100% and early cancer at 25% or 100% depending on your employer. Repeat claims wait 180 days in the designs we compared, and total pay stops at a 500% cap. Treat it as a cash supplement to real health insurance, and read your own certificate before you enroll.

Get Free Critical Illness Insurance Quotes

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

Hartford Critical Illness Insurance — Frequently Asked Questions

➤ Did the Equitable deal change who backs Hartford critical illness plans?

No. The Hartford bought Equitable’s employee benefits business, which it announced in August 2026 and completed in October 2026. Hartford’s own critical illness certificates are still issued by Hartford Life and Accident Insurance Company.

➤ What does severity-based mean on a Hartford plan?

The payout depends on how serious the diagnosis is. A severe stroke or a heart attack that needs open surgery can pay 100%, while milder forms pay 10% or 25% in the plan summaries reviewed.

➤ How much does a Hartford plan pay for early-stage cancer?

Carcinoma in situ paid 25% of the coverage amount in the Roanoke College and small-group summaries, and 100% in Jefferson County’s 2026 plan. Your employer’s design decides which applies.

➤ How long until the same illness can pay a second time?

In the designs compared here, a reoccurrence benefit is payable 180 days after a benefit was paid for that illness. The Hartford also offers employers a version with a 12-month separation period.

➤ Is there a limit on how much a Hartford policy pays in total?

Yes. Both employer plans reviewed cap critical illness benefits at 500% of the coverage amount for each covered person. The health screening payment does not count toward that cap.

➤ What is the Hartford health screening benefit worth?

It is a flat yearly payment for a covered preventive test such as a mammogram or colonoscopy, $50 or $75 per covered person in the summaries reviewed.

➤ Why does my Hartford critical illness plan not list cancer?

The Hartford lets an employer remove cancer when the group also offers a stand-alone cancer policy. In that case, cancer claims go through the separate cancer plan.

➤ Does Hartford critical illness coverage satisfy the ACA coverage requirement?

No. The Hartford’s materials say it provides limited benefits for specified diseases, is not major medical coverage and does not meet ACA minimum essential coverage requirements.

Cancer Insurance Quotes

Call a Licensed Agent Now

Compare cancer insurance plans and cash benefits from several insurance companies in one call.

☎ 1-888-891-0229

No obligation to buy

Ready to Compare? Get Free Cancer Insurance Quotes

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

ZRN Health & Financial Services, LLC, a Texas limited liability company