Updated November 2026
Key Takeaway
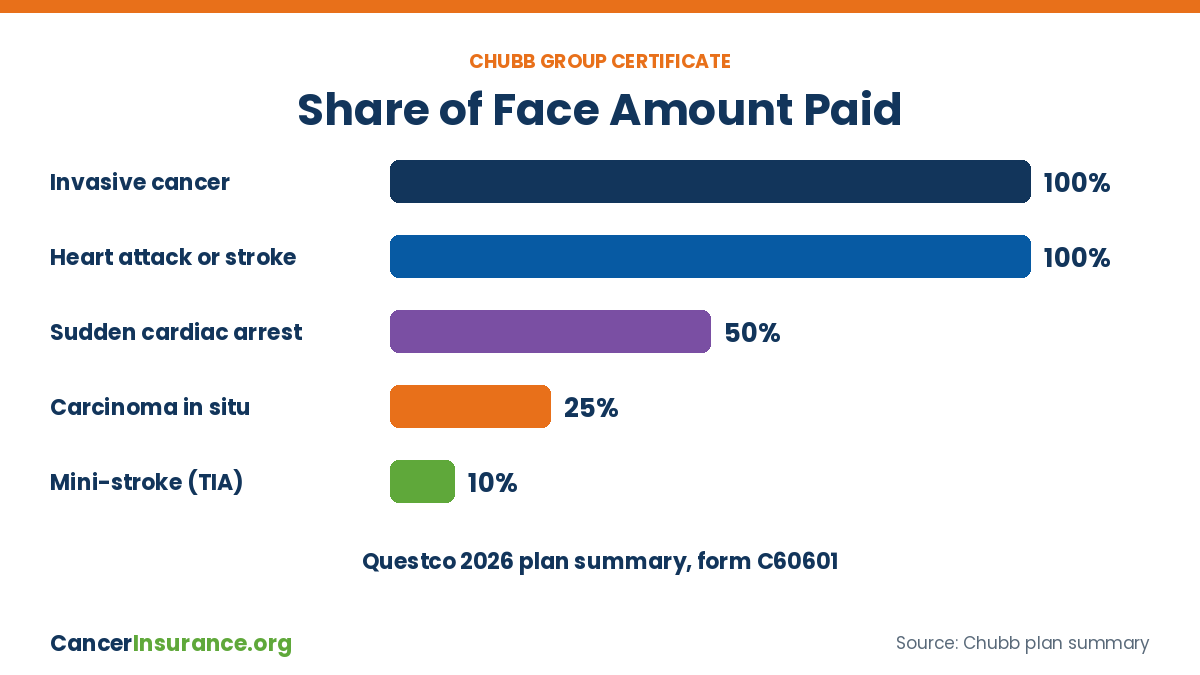
Chubb critical illness insurance is a supplemental group plan sold at work through Chubb Workplace Benefits, mostly issued by ACE Property and Casualty Insurance Company, that pays you a cash lump sum when you are diagnosed with a covered condition such as cancer, heart attack or stroke. Combined Insurance, another Chubb company, also markets a critical illness policy to individuals and families.
2027 by the Numbers
A+ (Superior)
AM Best rating for Combined Insurance Company of America, affirmed January 2026 (AM Best)
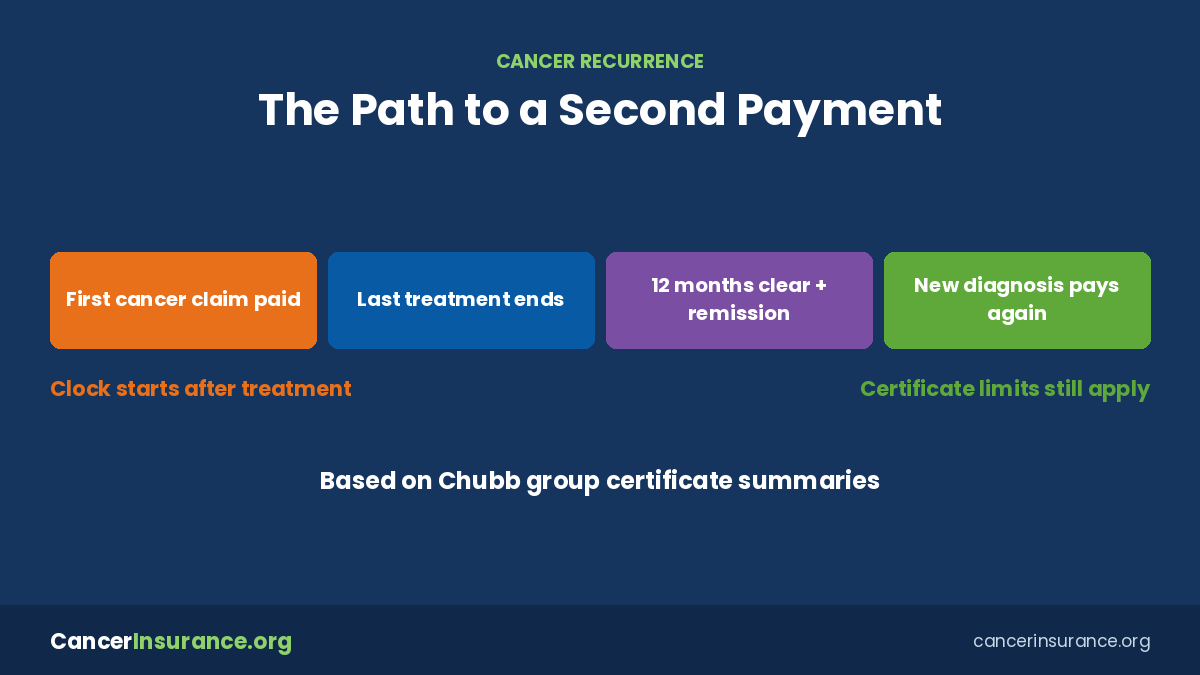
12 months
treatment-free time before a cancer recurrence can pay in the Chubb certificates we read (Chubb)
0 to 26
child ages covered in Chubb group designs, no student status needed (Chubb)
Chubb is one of the largest insurance groups in the world, but most people meet its critical illness coverage in one place: a payroll deduction offered during open enrollment. The plan pays a set amount of cash straight to you after a covered diagnosis. You decide how to spend it.
This guide breaks down what a Chubb certificate pays for cancer, why two coworkers at different companies can hold very different Chubb plans, how the recurrence rule works and what Chubb sells outside the workplace. Critical illness coverage is supplemental, limited-benefit insurance. It does not pay doctors, it is not major medical coverage and it does not replace health insurance through work, the ACA Marketplace or Medicare. For the basics of the product type, start with our critical illness insurance guide.