Speak with a licensed insurance agent

1-888-891-0229

Supplemental Health Insurance for Cancer: Types, Costs Covered and How It Pays

Updated October 2026

Key Takeaway

Supplemental health insurance for cancer is extra coverage that pays you cash after a covered cancer diagnosis or treatment, on top of your health plan. It is a limited-benefit policy that helps with deductibles, travel and lost income, but it does not replace health insurance.

A good health plan still leaves bills behind when cancer shows up. There is the deductible, the coinsurance, the drive to a treatment center, and the paychecks you may miss while you recover. Supplemental coverage is built for that gap.

This guide explains the four kinds of supplemental health insurance that help with cancer, how each one pays, how they fit with employer, ACA and Medicare coverage, and what to check before you buy. Every policy here is a supplemental, limited-benefit product that pays on top of your main plan. None of them replaces health insurance.
Compare Cancer Insurance Plans

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

What Supplemental Health Insurance for Cancer Is

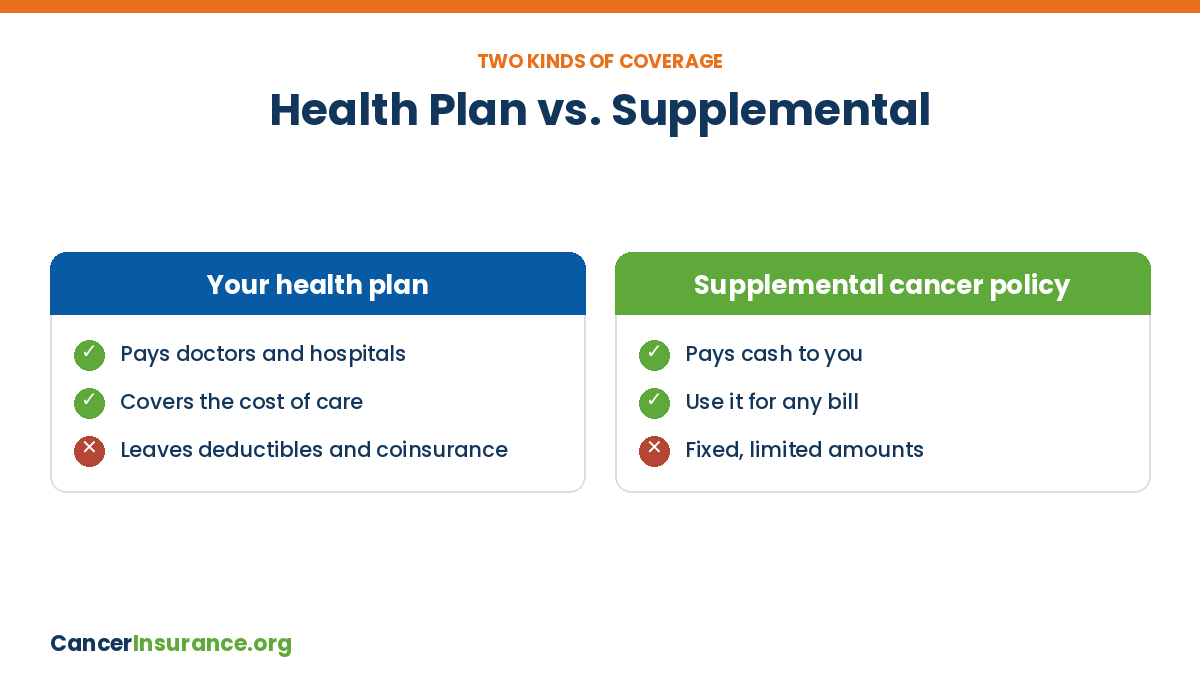
Major medical coverage compared with supplemental health insurance for cancer

Your health plan pays doctors and hospitals. A supplemental policy pays you. When a covered event happens, such as a cancer diagnosis, a hospital stay or a round of chemo, the insurer sends a set cash amount to you or someone you name. You decide how to spend it.

Cash to you. Benefits are not tied to your medical bills, so the money can go to rent, gas, groceries or a copay.

Paid on top. Most policies pay no matter what your health plan, Medicare or another policy already paid.

Limited by design. Each policy pays only the amounts on its benefit schedule, so it cannot cover every cost of care.

Because these policies pay fixed amounts instead of covering care, federal rules treat them as excepted benefits. That is why they do not count as health coverage on their own, and why they can have waiting periods and pre-existing condition limits that an ACA plan cannot.

Cancer Insurance Quotes

Call a Licensed Agent Now

Compare cancer insurance plans and cash benefits from several insurance companies in one call.

☎ 1-888-891-0229

No obligation to buy

Four Types of Supplemental Coverage That Help With Cancer

Several kinds of supplemental insurance can pay when you have cancer. They differ in what triggers a payment and how much flexibility you get.

TypeWhat triggers a paymentBest for
Cancer insuranceA covered cancer diagnosis, plus treatment, surgery or hospital benefits on many plansPeople who want coverage built around cancer care
Critical illness insuranceA lump sum after a listed illness, such as cancer, heart attack or strokePeople who want one policy for several serious illnesses
Hospital indemnity insuranceA daily or per-stay amount when you are admitted to a hospitalPlans with high hospital copays or coinsurance
Short-term disability insurancePart of your paycheck when illness keeps you from workingWorkers who could not cover bills without income

Benefits, names and availability vary by insurer and state. Read the outline of coverage for any policy you consider.

Broker tip: If cancer is your main worry, a cancer policy usually pays more for the same premium than a critical illness plan. If heart disease or stroke runs in your family too, critical illness coverage spreads the protection wider.

To see how the two most common choices differ in detail, read our guide to cancer insurance versus critical illness insurance.

How It Fits With Employer, ACA and Medicare Coverage

Supplemental cancer coverage works the same way no matter where your main coverage comes from. What changes is the size of the gap it has to fill.

Employer and ACA plans. For 2027, ACA-compliant plans can make you pay up to $12,000 a year for one person and $24,000 for a family before the plan pays 100% of covered in-network care.

Original Medicare. After the Part B deductible you usually pay 20% of outpatient costs such as chemo infusions and radiation, with no yearly cap unless you have a Medigap plan or other coverage.

Medicare Advantage and Part D. Medicare Advantage plans have their own yearly out-of-pocket limit, and in 2027 Part D caps what you pay for covered drugs at $2,400.

A policy sold to someone on Medicare does not replace Medigap, and the seller is expected to give a federal notice saying it is not Medicare Supplement insurance. Compare both before you buy, because a Medigap plan may close more of the gap for the money.

Lump Sum vs. Scheduled Benefits

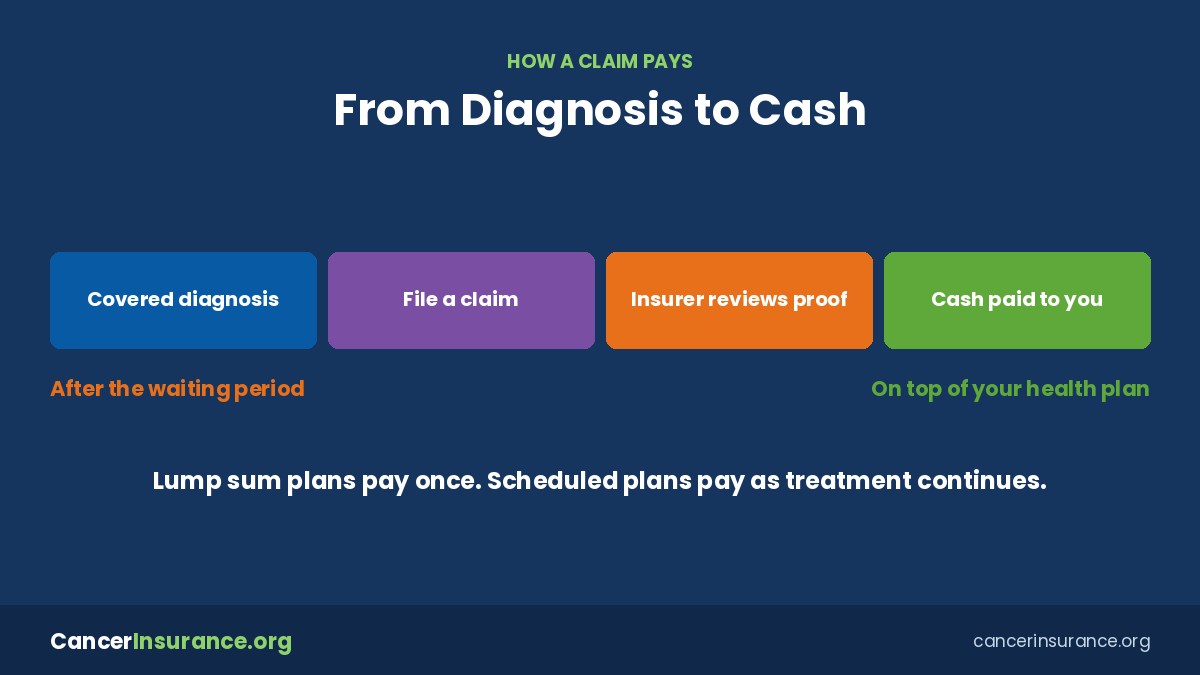
How supplemental health insurance for cancer pays from diagnosis to cash benefit

Supplemental cancer policies pay in one of two ways, and some combine both. A lump sum plan pays one check after a covered first diagnosis, often in a benefit amount you choose. A scheduled plan pays set amounts as care happens, such as so much per month of chemo or per day in the hospital.

A lump sum is simple and arrives early, when bills start. Scheduled benefits can add up to more during long treatment, but they pay less if treatment is short. Learn more about the first kind in our guide to lump sum cancer insurance.

Good to know: Some scheduled plans let you add a lump sum diagnosis rider, and some lump sum plans pay a smaller second benefit if cancer comes back after a set time. Ask how recurrence is handled before you choose.

Compare Cancer Insurance Plans

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

Fine Print to Check Before You Buy

Two policies with the same price can pay very differently. Check these points in the outline of coverage.

1

Waiting period. Many cancer policies do not pay for a cancer found in the first 30 days or more. See cancer insurance waiting periods explained.

2

Pre-existing limits. Most policies will not pay for a cancer you had before coverage, and some ask about cancer history going back years.

3

Covered cancers. Skin cancers other than melanoma often pay a smaller benefit or none at all, and early-stage cancers may pay a reduced amount.

4

Renewability. Look for guaranteed renewable coverage, so the insurer cannot cancel you because of a claim.

5

Insurer strength. Check the company’s AM Best rating to see its ability to pay claims years from now.

How to Decide and Where to Buy

Start with your gap. Add your health plan’s out-of-pocket maximum, the travel and household costs your plan never pays, and the income you could lose. Subtract the savings you would use. What is left is the amount a supplemental policy should cover.

At work. Employers often offer cancer, critical illness and hospital plans at open enrollment, with easy payroll deduction.

On your own. Individual policies stay with you if you change jobs or retire, and you can compare several insurers at once.

Before a diagnosis. Buy while you are healthy, since most policies limit or deny coverage once cancer is found.

Ready to look at options? Start with our 5 best cancer insurance policies or browse all cancer insurance plans.

Bottom Line

Supplemental health insurance for cancer pays you cash when cancer creates costs your health plan leaves behind. Cancer, critical illness, hospital indemnity and disability coverage each fill a different part of that gap. Size the policy to your out-of-pocket maximum and lost income, check the fine print, and buy while you are healthy.

Get Free Cancer Insurance Quotes

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

Supplemental Health Insurance for Cancer — Frequently Asked Questions

➤ What is supplemental health insurance for cancer?

It is a limited-benefit policy that pays you set cash amounts after a covered cancer diagnosis or treatment. It works on top of your health plan and does not replace health insurance.

➤ Does supplemental cancer insurance replace my health plan?

No. It pays fixed amounts instead of covering care, so it cannot pay for treatment the way a health plan does. It is meant to help with deductibles, coinsurance, travel and household bills.

➤ Is cancer insurance or critical illness insurance better?

Cancer insurance focuses only on cancer and often pays more for that one risk. Critical illness insurance pays a lump sum for several listed illnesses, such as cancer, heart attack and stroke. The right choice depends on your family history and budget.

➤ Can I buy supplemental cancer insurance if I have Medicare?

Yes, many insurers sell cancer policies to people on Medicare. It does not replace Medigap, so compare a Medigap plan and a cancer policy before you decide.

➤ Will supplemental cancer insurance pay if I already have cancer?

Usually not for that cancer. Most policies exclude cancers diagnosed before coverage starts or during the waiting period, and many ask about cancer history on the application.

➤ How is a supplemental cancer policy paid out?

Some plans pay one lump sum after a first diagnosis. Others pay scheduled amounts for treatment, surgery and hospital days. Money goes to you unless you assign it to a provider.

➤ Is supplemental cancer insurance expensive?

It is usually one of the lower-cost types of coverage, but the price depends on your age, the benefit amount, who is covered and whether you buy through work.

➤ Can I have more than one supplemental policy?

Yes. Many people pair a cancer or critical illness policy with hospital indemnity or disability coverage. Most supplemental policies pay regardless of other coverage, but check each policy’s rules.

Cancer Insurance Quotes

Call a Licensed Agent Now

Compare cancer insurance plans and cash benefits from several insurance companies in one call.

☎ 1-888-891-0229

No obligation to buy

Ready to Compare? Get Free Cancer Insurance Quotes

Speak with a licensed insurance agent

1-888-891-0229

CancerInsurance.org logo

ZRN Health & Financial Services, LLC, a Texas limited liability company